


Production royalty

Since 2015, the production royalty is a state-wide tax that is paid for the use of subsoil for the extraction of minerals; for using the subsoil for purposes not related to the extraction of minerals; for using the radio frequency resource of Ukraine; for special use of water; for special use of forest resources; for the transportation of oil and petroleum products by main oil pipelines and petroleum product pipelines, transit transportation of natural gas and ammonia by pipelines through the territory of Ukraine.

The taxable object was the volume of commodity products of the mining enterprise - extracted minerals (mineral raw materials) (hereinafter referred to as minerals) in the respective tax period, the type of which was established by the conditions for mineral raw materials of the subsoil object (site). The Tax Code also determines the cases when extracted minerals are not included in the taxable object for the purposes of charging production royalty.
The tax base was the value of the volume of mineral resources extracted during the reporting period, calculated separately for each type of mineral commodity (mineral raw material) and for each subsoil area based on the standard delivery terms (finished products warehouse of the mining enterprise).
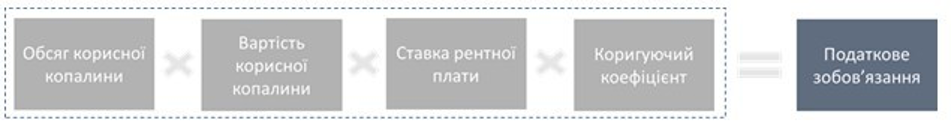
To calculate the tax liability, taxpayers were required to determine the following key parameters for the relevant reporting period: the volume of mineral commodities extracted, the value of such production, the applicable tax rate, and the adjustment coefficient.
Production Royalty calculator
The Production Royalty Calculator is an online tool designed to estimate royalty payments and the carbon footprint associated with mineral production.
Enter the required data to calculate estimated royalty payments and see how these revenues are distributed across different levels of government. The tool also automatically estimates the carbon footprint associated with the extraction of the specified volume of mineral commodities.
Production Royalty calculator
Loading...

The temporary rules for calculating the value of natural gas for the purposes of calculating the production royalty, introduced during the martial law, continued to apply in 2024.
-
►
Before the ban on the export of natural gas outside the customs territory of Ukraine is lifted, the calculation of the cost of natural gas is tied to the prices on the domestic market using the maximum of three values, which were published by the Ministry of Economy on its website by the 10th day of the month following the reporting period.
-
►
The rule regarding the payment of production royalty only for sold gas also continued to apply.
-
►
For natural gas sold by Naftogaz of Ukraine NJSC to form a natural gas resource for household consumers and heat energy producers, the value was the price specified in the natural gas purchase and sale agreements between the production royalty payer and Naftogaz of Ukraine NJSC in the reporting period. Starting 01.12.2024, the actual sale price of natural gas was converted into US dollars at the arithmetic average official exchange rate of the National Bank of Ukraine for the tax (reporting) period.
-
►
For oil and condensate: The Ministry of Economy calculated the average cost of one barrel of Ural oil according to the information from an international agency (UralsMediterranean and UralsRotterdam quotes), converted into UAH per ton at the rate of the National Bank of Ukraine as of the 1st day of the month following the tax (reporting) period (and such cost was published on the official website of the Ministry of Economy).
When carrying out controlled transactions in the cases specified by the Tax Code, the actual selling price should have been not less than the price determined at the arm's length rule.
The temporary rules for calculating the value of natural gas for the purposes of calculating the production royalty, introduced during the martial law, continued to apply in 2023.
For natural gas:
In 2023, the temporary rules for calculating the value of natural gas for the purposes of calculating the rent for the use of subsoil, introduced as a result of martial law, continued to apply:
► In 2023, temporary rules for calculating the value of natural gas for the purposes of calculating the production royalty, which were introduced due to the martial law, continued to apply:
► Until the ban on the export of natural gas out of the customs territory of Ukraine is lifted, the calculation of the value of natural gas will be tied to the prices in the domestic market using the bigger of the following as a factor:
► the weighted average price in the contracts of Naftogaz of Ukraine NJSC concluded for purchasing natural gas of own production on the organized commodity markets.
► the weighted average selling price for natural gas according to the results of trading on organized commodity markets excluding VAT, in UAH per 1000 cubic meters, in the month preceding the reporting month, excluding Naftogaz of Ukraine NJSC and the enterprises in whose authorized capital Naftogaz of Ukraine NJSC has a share of 50% or more.
► the arithmetic mean of the average UA VTP Gas price for the following month.
► The Ministry of Economy publishes the specified indicators on its website by the 10th day of the month following the reporting period.
► The rule for payment of production royalty only for the gas sold also continued to apply.
For natural gas sold by Naftogaz of Ukraine NJSC to form a natural gas resource for household consumers and heat energy producers, the value was the price specified in the natural gas purchase and sale agreements between the production royalty payer and Naftogaz of Ukraine NJSC in the reporting period.
For oil and condensate: The Ministry of Economy calculated the average value of one barrel of Urals according to information from an international agency (UralsMediterranean and UralsRotterdam quotes), converted into UAH per ton at the NBU exchange rate as of the 1st day of the month following the tax (reporting) period (these indicators was published on the official website of the Ministry of Economy).
When carrying out controlled transactions in the cases specified by the Tax Code, the actual selling price should have been not less than the price determined at the arm's length rule.
The tax base for the production royalty for subsoil use for the extraction of hydrocarbons was the value of commodities, namely minerals extracted during the reporting period, calculated according to special rules that changed several times during 2022:
-
1.
For natural gas:
Until March 2022, the Ministry of Economy calculated the average customs value of imported natural gas established during its customs clearance upon importation into Ukraine in the tax period. This value was published on the official website of the Ministry of Economy.
► In March 2022, following the introduction of martial law, the procedure for determining the value of natural gas for the purposes of calculating the production royalty was amended and the production royalty rates were increased. The value of natural gas was to be determined as the arithmetic mean of: the average customs value of imported natural gas established during its customs clearance upon importation into Ukraine in the tax period; and the arithmetic mean of natural gas price quotations for the reporting month, namely Front Month Settlement Prices at the Dutch gas hub TTF, according to information from the European Energy Exchange (EEX), established during the calendar month preceding the tax (reporting) period and calculated by the Ministry of Economy per 1,000 cubic meters in US dollars and in the national currency of Ukraine, excluding VAT, using the arithmetic average official exchange rate of the National Bank of Ukraine for the tax (reporting) period.
Linking the calculation of the production royalty to global gas prices, together with the introduction of differentiated production royalty rates depending on the selling price, increased the tax burden on extractive companies.
► In April 2022, the payment of production royalty only for natural gas sold was temporarily introduced.
► Subsequently, in order to stabilize and reduce the tax burden on production royalty payers for subsoil use for natural gas extraction, temporary rules were introduced. Until the ban on the export of natural gas outside the customs territory of Ukraine is lifted, the calculation of the value of natural gas extracted from 1 August 2022 was tied to prices on the domestic market using the highest of the following values:
- the weighted average price under the contracts of Naftogaz of Ukraine NJSC concluded for the purchase of natural gas of its own production on organized commodity markets;
- the weighted average selling price for natural gas based on the results of trading on organized commodity markets, excluding VAT, in UAH per 1,000 cubic meters, in the month preceding the reporting month, excluding Naftogaz of Ukraine NJSC and enterprises in which Naftogaz of Ukraine NJSC holds 50% or more of the authorized capital;
- the arithmetic mean of the average UA VTP Gas price for the following month.The Ministry of Economy publishes these indicators on its website by the 10th day of the month following the reporting period.
-
2.
For natural gas sold
Natural gas (of any origin) from deposits at a depth of up to 5000 m
Natural gas (of any origin) from deposits at a depth of up to 5000 m Naftogaz of Ukraine NJSC to form a natural gas resource for household consumers and heat energy producers, the value was the price specified in the natural gas purchase and sale agreements between the production royalty payer and Naftogaz of Ukraine NJSC in the reporting period.
-
3.
For oil and condensate: The Ministry of Economy calculated the average value of one barrel of Urals oil according to information from an international agency, based on Urals Mediterranean and Urals Rotterdam quotations, converted into UAH per tonne at the exchange rate of the National Bank of Ukraine as of the first day of the month following the tax (reporting) period. This value was published on the official website of the Ministry of Economy.
When carrying out controlled transactions in the cases specified by the Tax Code, the actual selling price of the relevant commodity of a mining enterprise, namely the extracted mineral or mineral raw material, could not be lower than the price determined according to the arm’s length principle.
The production royalty rates for subsoil use for the extraction of minerals were established by the Tax Code. In March 2022, a mechanism of differentiated production royalty for natural gas was introduced, under which production royalty rates depended on the selling price of natural gas, thereby increasing the tax burden on extractive companies. At the same time, stabilization of the production royalty rates was introduced: the State guarantees that the new production royalty rates cannot be increased until March 2032.
In 2021, the tax base for the production royalty for the use of subsoil for the extraction of hydrocarbons was the value of commodities, namely minerals extracted during the reporting period, calculated according to special rules.
-
►
For natural gas: The Ministry of Economy calculated the average customs value of imported natural gas established during its customs clearance upon importation into Ukraine in the tax period. This value was published on the official website of the Ministry of Economy.
-
►
For natural gas sold by Naftogaz of Ukraine NJSC: To form a natural gas resource for household consumers and heat energy producers, the value was the price specified in the natural gas purchase and sale agreements between the production royalty payer and Naftogaz of Ukraine NJSC in the reporting period.
-
►
For oil and condensate: The Ministry of Economy calculated the average value of one barrel of Urals oil according to information from an international agency (Urals Mediterranean and Urals Rotterdam quotations), converted into UAH per tonne at the exchange rate of the National Bank of Ukraine as of the 1st day of the month following the tax (reporting) period. This value was published on the official website of the Ministry of Economy.
-
►
When carrying out controlled transactions in the cases specified by the Tax Code, the actual selling price of the relevant commodity product of a mining enterprise, namely the extracted mineral (mineral raw material), could not be lower than the price determined in accordance with the arm’s length principle.
The rates of production royalty for the subsoil use for hydrocarbons
The production royalty rates for the use of subsoil for the extraction of minerals were established by the Tax Code.
Royalty rates for subsoil use in hydrocarbon production in 2024
| Object of taxation | Tax rate |
|---|---|
| Oil | |
| from deposits at a depth of up to 5000 m | 31% |
| from deposits at a depth of more than 5000 m | 16% |
| extracted under PSA | 2% |
| Condensate | |
| from deposits at a depth of up to 5000 m | 31% |
| from deposits at a depth of more than 5000 m | 16% |
| extracted under PSA | 2% |
| Natural gas (of any origin) | |
| from deposits at a depth of up to 5000 m | 14,5 %-65% (before 30.11.2024) 29 %-65% (starting 01.12.2024) |
| from deposits at a depth of more than 5000 m | 7%-31% (before 30.11.2024) 14%-31% (starting 01.12.2024) |
| from deposits in subsoil areas (fields) within the continental shelf and/or exclusive (maritime) economic zone of Ukraine | 11% |
| extracted under JVA | 70% |
| extracted under PSA | 1,25% |
| from new wells from deposits at a depth of up to 5000 m | 6%-36% (before 30.11.2024) 12%-36% (starting 01.12.2024) |
| from new wells from deposits at a depth of more than 5000 m | 3%-18% (before 30.11.2024) 6%-18% (starting 01.12.2024) |
In 2023, a mechanism of differentiated production royalty for natural gas was in place, according to which the rates of production royalty depended on the sales price. At the same time, stabilization of production royalty rates continued: the State guarantees that the new production royalty rates cannot increase until March 2032.
Royalty rates for subsoil use in hydrocarbon production in 2023
| Object of taxation | Rate |
|---|---|
| Oil | |
| from deposits at a depth of up to 5000 m | 31% |
| from deposits at a depth of more than 5000 m | 16% |
| extracted under PSA | 2% |
| Condensate | |
| from deposits at a depth of up to 5000 m | 31% |
| from deposits at a depth of more than 5000 m | 16% |
| extracted under PSA | 2% |
| Natural gas (of any origin) | |
| from deposits at a depth of up to 5000 m | 14.5%-65% |
| from deposits at a depth of more than 5000 m | 7%-31% |
| from deposits in subsoil areas (fields) within the continental shelf and/or exclusive (maritime) economic zone of Ukraine | 11% |
| extracted under JVA | 70% |
| extracted under PSA | 1.25% |
| from new wells from deposits at a depth of up to 5000 m | 6%-36% |
| from new wells from deposits at a depth of more than 5000 m | 3%-18% |
For natural gas, in most cases, a differentiated production royalty applied, depending on its selling price.
From 01.12.2024, a law came into force abolishing the reduced rate for the cases where the actual selling price of natural gas for the reporting period is USD 150 or less for 1000 cubic meters.
Actual natural gas production royalty rates in 2024 for the cases where the rate varied depending on the USD equivalent of the actual selling price. Since the price was more than USD 150 but less than USD 400, the rates remained stable throughout 2024.
Natural gas production royalty rates in 2024 subject to the actual selling price of natural gas in 2024
| Month, 2024 | Actual sales price determined by the Ministry of Economy, UAH per 1000 cubic meters | Equivalent to the actual sale price, determined by the Ministry of Economy in USD | from deposits at a depth of up to 5000 m | from deposits at a depth of more than 5000 m | from new wells from deposits at a depth of up to 5000 m | from new wells from deposits at a depth of more than 5000 m |
|---|---|---|---|---|---|---|
| January | 12,738.16 | 339.12 | 29% | 14% | 12% | 6% |
| February | 12,180.30 | 320.12 | 29% | 14% | 12% | 6% |
| March | 11,621.27 | 298.00 | 29% | 14% | 12% | 6% |
| April | 11,124.26 | 281.52 | 29% | 14% | 12% | 6% |
| May | 12,460.08 | 307.66 | 29% | 14% | 12% | 6% |
| June | 12,563.31 | 310.56 | 29% | 14% | 12% | 6% |
| July | 12,699.09 | 309.69 | 29% | 14% | 12% | 6% |
| August | 12,994.71 | 315.48 | 29% | 14% | 12% | 6% |
| September | 14,500.00 | 351.77 | 29% | 14% | 12% | 6% |
| October | 14,405.82 | 349.49 | 29% | 14% | 12% | 6% |
| November | 14,945.69 | 359.31 | 29% | 14% | 12% | 6% |
| December | 15,287.63 | 363.74 | 29% | 14% | 12% | 6% |
When calculating the production royalty, adjusting coefficients (from 0.01 to 0.97) were used depending on the type of raw material and the conditions of its extraction.
-
►
PSA. The rates of fees for subsoil use or production royalty were determined in the PSA, but they could not be lower than those established by Section IX of the Tax Code at the time of conclusion of the PSA.
In 2024, special production royalty rates continued to apply:
- For oil and condensate, the production royalty for the extraction of minerals was calculated at a rate of 2% of the value of the mining enterprise's commodity products.
- For natural gas, the production royalty for the extraction of minerals was calculated at a rate of 1.25% of the value of the mining enterprise's commodity products.
-
►
For legal entities that meet the established criteria for state ownership, a special rate was provided for charging tax on the additional volumes of hydrocarbon raw materials extracted as a result of the implementation of existing or new investment projects that provide for the increase in hydrocarbon raw material production in the amount of 2% of the value of additional extraction of the relevant hydrocarbon raw materials at specified sites and wells.
The procedure for selecting and approving such new investment projects/programs, as well as the procedure for monitoring their implementation, are determined by the CMU upon submission by the Ministry of Economy. The list of subsoil areas and/or subsoil area objects where new investment projects are implemented is determined by the Ministry of Energy.
Actual rates applied to the volumes of natural gas extracted during 2023, which were determined depending on the USD equivalent of the actual sales price in the domestic market (the rates specified in the table do not apply to the cases where the production royalty was calculated and paid for the gas extracted from deposits in subsoil areas (fields) within the continental shelf and/or exclusive (maritime) economic zone of Ukraine, natural gas extracted during under JVAs or PSAs, since in these cases the rate remained unchanged and did not depend on the actual sales price).
Natural gas production royalty rates in 2024 subject to the actual selling price of natural gas in 2023
| Month, 2023 | Actual sales price determined by the Ministry of Economy, UAH per 1000 cubic meters | Equivalent to the actual sale price, determined by the Ministry of Economy in USD | from deposits at a depth of up to 5000 m | from deposits at a depth of more than 5000 m | from new wells from deposits at a depth of up to 5000 m | from new wells from deposits at a depth of more than 5000 m |
|---|---|---|---|---|---|---|
| January | 23,723.43 | 648.74 | 65% | 31% | 36% | 18% |
| February | 20,727.73 | 566.82 | 65% | 31% | 36% | 18% |
| March | 18,680.83 | 510.84 | 65% | 31% | 36% | 18% |
| April | 14,382.34 | 393.30 | 29% | 14% | 12% | 6% |
| May | 11,163.77 | 305.28 | 29% | 14% | 12% | 6% |
| June | 10,742.81 | 293.77 | 29% | 14% | 12% | 6% |
| July | 10,833.33 | 296.25 | 29% | 14% | 12% | 6% |
| August | 12,500.00 | 341.82 | 29% | 14% | 12% | 6% |
| September | 14,849.72 | 406.08 | 65% | 31% | 36% | 18% |
| October | 15,196.24 | 418.85 | 65% | 31% | 36% | 18% |
| November | 14,380.68 | 395.58 | 29% | 14% | 12% | 6% |
| December | 13,595.70 | 357.76 | 29% | 14% | 12% | 6% |
When calculating the production royalty for the subsoil use, the adjustment coefficients (from 0.01 to 0.97) apply depending on the type of raw material and the conditions of its extraction.
Compared to the rates at the end of 2022, the rates of production royalty for the extraction of oil, condensate and natural gas did not change in 2023. In October 2024, the VRU adopted the law that, inter alia, provided for the abolition of the reduced production royalty rate when the actual sale price of natural gas for the reporting period is USD 150 or less per 1000 cubic meters. The law entered into force on 01.12.2024
The rates of the production royalty for the subsoil use or the production royalty under PSA were determined in the PSA, but they could not be lower than those established by Section IX of the Tax Code at the time of the PSA conclusion. In 2023, special production royalty rates continued to apply: under the PSA for oil and condensate, the production royalty for the subsoil use was calculated at a rate of 2% of the value of the mining enterprise's commodities, and for natural gas, the production royalty for the subsoil use was calculated at a rate of 1.25% of the value of the mining enterprise's commodities.
For legal entities that meet the specified criteria for state ownership, a special rate is provided for taxation of additional volumes of hydrocarbon raw materials extracted as a result of the implementation of existing or new investment projects that provide for an increase in hydrocarbon raw materials extraction in the amount of 2% of the cost of additional extraction of the relevant hydrocarbon raw material for:
-
►
subsoil areas with deteriorated mining and geological conditions (which are difficult to extract) or depleted during development in previous periods;
-
►
individual operating wells after major repairs;
-
►
wells restored from the liquidated ones, new wells or groups of wells located in such subsoil areas.
The procedure for selecting and approving new investment projects that provide for the increase in hydrocarbon raw materials extraction, the procedure for determining additional volumes of hydrocarbon raw materials, as well as the procedure for monitoring the implementation of such investment projects (programs) are determined by the CMU upon submission by the Ministry of Economy.
The list of subsoil fields and/or subsoil areas where the new investment projects are implemented is determined by the Ministry of Energy.
Royalty rates for subsoil use in hydrocarbon production in 2022
| Object of taxation | Rate |
|---|---|
| Oil | |
| from deposits at a depth of up to 5000 m | 31 % |
| from deposits at a depth of more than 5000 m | 16 % |
| extracted under PSA | 2% |
| Condensate | |
| from deposits at a depth of up to 5000 m | 31 % |
| from deposits at a depth of more than 5000 m | 16 % |
| extracted under PSA | 2% |
| Natural gas (of any origin) | |
| from deposits at a depth of up to 5000 m | 29 % |
| Starting from March 2022: from deposits at a depth of up to 5,000 m | 14,5 % - 65 % |
| Before March 2022: from deposits at a depth of more than 5,000 m, including natural gas sold for household consumers | 14 % |
| Starting from March 2022: from deposits at a depth of more than 5,000 m | 7 % - 31 % |
| from deposits in subsoil areas (fields) within the continental shelf and/or exclusive (maritime) economic zone of Ukraine | 11 % |
| extracted under JVA | 70 % |
| extracted under PSA | 1,25 % |
| Before March 2022: natural gas extracted from new wells from deposits wholly or partially located at a depth of up to 5,000 m | 12 % |
| Starting from March 2022: natural gas extracted from new wells from deposits wholly or partially located at a depth of up to 5,000 m | 6 % - 36 % |
| Before March 2022: natural gas extracted from new wells from deposits wholly or partially located at a depth of more than 5,000 m | 6 % |
| З березня 2022 року: природний газ, видобутий із нових свердловин з покладів, які повністю або частково залягають на глибині понад 5000 метрів | 3 % - 18 % |
When calculating the production royalty for subsoil use, adjustment coefficients (from 0.01 to 0.97) applied depending on the type of raw material and the conditions of its extraction.
Compared to the rates applicable in 2021, the rates of production royalty for the extraction of oil, condensate and natural gas increased in 2022.
The rates of the production royalty for subsoil use or the production royalty under PSA were determined in the PSA, but they could not be lower than those established by Section IX of the Tax Code at the time of the PSA conclusion. In 2022, special production royalty rates continued to apply: under the PSA for oil and condensate, the production royalty for subsoil use for the extraction of minerals was calculated at a rate of 2% of the value of the mining enterprise's commodity products, while for natural gas, the production royalty for subsoil use for the extraction of minerals was calculated at a rate of 1.25% of the value of the mining enterprise's commodity products.
Temporary specific features of payment of production royalty for the subsoil use for gas extraction
In 2023–2024, temporary specific features of production royalty payment for subsoil use related to natural gas extraction remained in effect for volumes of natural gas injected into storage facilities and not sold. In particular:
-
►
The production royalty for the subsoil use for natural gas extraction is temporarily not paid for the volumes of extracted natural gas which were pumped into gas storage facilities.
-
►
The amount of tax liabilities of production royalty for the subsoil use for natural gas extraction in each reporting period is calculated for the volumes of the extracted natural gas in the relevant tax (reporting) period but will be paid in the amount corresponding to the volumes of natural gas sold in such tax (reporting) period.
-
►
The amount of the production royalty due is calculated as the difference between the declared tax liabilities and the product of the volume of the pumped natural gas and the weighted average effective rate.
-
►
In the case of the sale of natural gas pumped into gas storage facilities, the amount of tax liabilities of production royalty is calculated according to the FIFO principle, based on the weighted average effective production royalty rate and the volume of gas written off from the balance sheet of gas stored in the gas storage facility.
-
►
Production royalty payers are required to keep separate records of the volumes of natural gas extracted and sold.
-
►
If the balance of unsold gas is available at the end of the month in which martial law is terminated, the amount of the tax liabilities will be paid in the period when the sale takes place, but no later than the end of the third month after the termination or cancellation of martial law in the territory of Ukraine.
The temporary provisions do not apply to the volumes of natural gas sold to Naftogaz of Ukraine NJSC to form a natural gas resource for the needs of household consumers and heat energy producers.
The special rules for paying production royalty will be in effect until the last day of the month in which martial law is lifted in the territory of Ukraine.
For the purposes of reducing the tax burden on natural gas production companies following the March 2022 changes to the production royalty calculation rules, a temporary special mechanism for the payment of production royalty for subsoil use in respect of volumes of natural gas injected into gas storage facilities and not sold was introduced in April 2022. In particular:
-
►
The production royalty for subsoil use for natural gas extraction was temporarily not paid in respect of volumes of natural gas extracted but not sold during the relevant reporting periods and injected into gas storage facilities.
-
►
The amount of tax liabilities for the production royalty for subsoil use for natural gas extraction in each reporting period was calculated based on the volume of natural gas extracted during the relevant tax (reporting) period, but was payable only in the amount corresponding to the volume of natural gas sold during such tax (reporting) period.
-
►
The amount of production royalty payable was calculated as the difference between the declared tax liabilities and the product of the volume of natural gas injected into storage facilities and the weighted average effective production royalty rate.
-
►
In the case of the sale of natural gas injected into storage facilities from April 2022 onwards, the amount of production royalty liabilities was calculated according to the FIFO principle, based on the weighted average effective production royalty rate and the volume of gas written off from the balance sheet of gas stored in the gas storage facility.
-
►
Production royalty payers were required to keep separate records of the volumes of natural gas extracted and sold.
-
►
If a balance of unsold gas remained at the end of the month in which martial law was terminated, the amount of tax liabilities would be paid in the period when the sale took place, but not later than the end of the third month following the termination or cancellation of martial law in the territory of Ukraine.
The temporary provisions did not apply to volumes of natural gas sold to Naftogaz of Ukraine NJSC to form a natural gas resource for household consumers and heat energy producers.
The special rules for the payment of production royalty will remain in effect until the last day of the month in which martial law is terminated in the territory of Ukraine.
In 2021, special production royalty rates were in effect: under the PSA for oil and condensate, the production royalty for subsoil use for the extraction of minerals was calculated at a rate of 2% of the value of the mining enterprise’s commodity products, and for natural gas, the production royalty for subsoil use for the extraction of minerals was calculated at a rate of 1.25% of the value of the mining enterprise’s commodity products.
The size of rent rates for the use of subsoil in the case of extraction of hydrocarbon raw materials in 2021
| Object of taxation | Rate |
|---|---|
| Oil | |
| from deposits at a depth of up to 5000 m | 31 % |
| from deposits at a depth of more than 5000 m | 16 % |
| Condensate | |
| from deposits at a depth of up to 5000 m | 31 % |
| from deposits at a depth of more than 5000 m | 16 % |
| Natural gas (of any origin) | |
| from deposits at a depth of up to 5000 m | 29 % |
| Starting from March 2022: from deposits at a depth of up to 5,000 mfrom deposits at a depth of more than 5,000 m, sold for the needs of household consumers | 14 % |
| from deposits in subsoil areas (fields) within the continental shelf and/or exclusive (maritime) economic zone of Ukraine | 11 % |
| from deposits at a depth of up to 5,000 m, sold for the needs of household consumers | 29 % |
| from deposits at a depth of more than 5,000 m, sold for the needs of household consumers | 14 % |
| extracted under JVA | 70 % |
| natural gas extracted from new wells from deposits wholly or partially located at a depth of up to 5,000 m (except for natural gas extracted under JVA) | 12 % |
| natural gas extracted from new wells from deposits wholly or partially located at a depth of more than 5,000 m (except for natural gas extracted under JVA) | 6 % |
Compared to the rates applicable in 2020, the rates of production royalty for the extraction of oil, condensate and natural gas did not change in 2021.
The size of rent rates for the use of subsoil in the case of extraction of hydrocarbon raw materials in 2020.
| Object of taxation | Rate |
|---|---|
| Oil | |
| extracted from deposits located at depths of under 5,000 m | 31 % |
| extracted from deposits located at depths of over 5,000 m | 16 % |
| Condensate | |
| extracted from deposits located at depths of under 5,000 m | 31 % |
| extracted from deposits located at depths of over 5,000 m | 16 % |
| Natural gas (of any origin) | |
| extracted from deposits located at depths of under 5,000 m | 29 % |
| extracted from deposits located at depths of over 5,000 m | 14 % |
| extracted from deposits in subsoil fields located within the continental shelf and/or the exclusive (maritime) economic zone of Ukraine | 11 % |
| extracted from deposits located at depths of under 5,000 meters, sold for households’ needs | 29 % |
| extracted from deposits located at depths of over 5,000 meters, sold for households’ needs | 14 % |
| produced under JVA | 70 % |
From January 1, 2018, a stimulating royalty rate was introduced for extracting natural gas, produced from new wells in the amount of 12% of the deposits that are fully or partially located at depths of under 5000 meters, and 6% of the deposits that are fully or partially located at a depth of over 5000 meters. In 2019, royalty rates for extracting oil were standardized
In 2018, 5% of the production royalty for extracting hydrocarbons were transferred to the general fund of the local budgets, which was distributed depending on the location (place of extraction) of the respective natural resources. The amount of 95% of this tax was transferred to the State budget, except for the payments made for the use of natural resources within the continental shelf or exclusive (marine) economic territory of Ukraine, which had to be remitted to the State budget in full

The basis of taxation for minerals, other than hydrocarbon raw materials and iron ores, is their value, which was calculated according to the greater of two values: according to the actual sale prices or according to the estimated value of the mineral.
Calculation of the actual selling price of a mineral
As a general rule, the amount of revenue generated from the sale of a particular mineral commodity during the reporting period was reduced by the exhaustive list of deductible expenses established by the Tax Code.
In the years 2020-2024, as in previous years, the expenses included:
- the costs of delivering products to the consumer and the costs of pre-sale preparation of goods.
- In the absence of sales of extracted minerals or if there is a need to subject such extracted minerals to technological operations that are not provided for by primary processing for the introduction of extracted minerals into civil circulation, the tax base for production royalty is determined based on the estimated value.
- a special rule is used for calculating the value of uranium and gold ores extracted from primary deposits.
The unit cost of a type of mineral extracted was calculated as the ratio of the amount of income from the sale of a type of mineral extracted (with deduction of costs) and the volume (quantity) of the corresponding type of mineral sold of minerals, which is determined according to the accounting data of stocks of finished products of such payer.
At the end of 2024, laws came into force that, inter alia, changed the mechanism for calculating the value of extracted minerals for the purposes of production royalty by establishing a minimum tax base for paying production royalty for:
-
►
granite: USD 6.5 per ton or more
-
►
sand: USD 5 per ton or more
-
►
kaolin: USD 300 per ton or more, and from 01.01.2025 – 120 USD per 1 ton if extracted from mineral raw materials recognized as suitable for primary processing (enrichment), USD 40 per 1 ton if extracted from mineral raw materials recognized as unsuitable for primary processing (enrichment).
Production royalty rates for subsoil use in case of extraction of types of minerals, other than hydrocarbons and iron ore, 2022 - 2024
| Object of taxation | Rate |
|---|---|
| Ore (metal-bearing (metallic), including ores) minerals: | |
| ferrous (other than iron one), colour and alloying metals | 6.25 % |
| uraniferous, and other than uriniferous ores of ferrous, colour and alloying metals | 5 % |
| Energy minerals | |
| coking coal | 1.5 % |
| energy coal | 0.75 % |
| anthracite | 1 % |
| brown | 1 % |
| Non-energy, non-ore (non-metal-containing (non-metal)) minerals, including quartz sand, groundwaters, fire clay, high-melting clay, limestone, granite, gneiss, therapeutic muds and others, except for amber) | 5 % |
The size of rent rates for the use of subsoil in the case of extraction of other types of minerals, except for hydrocarbons, in 2021.
| Object of taxation | Rate |
|---|---|
| Ore (metal-bearing (metallic), including ores) minerals: | |
| ferrous (other than iron one), colour and alloying metals | 6,25 % |
| uraniferous, and other than uriniferous ores of ferrous, colour and alloying metals | 5 % |
| Iron ores | 11-12 % |
| Energy minerals | |
| coking coal | 1,5 % |
| energy coal | 0,75 % |
| anthracite | 1 % |
| brown | 1 % |
| Non-energy, non-ore (non-metal-containing (non-metal)) minerals, including quartz sand, groundwaters, fire clay, high-melting clay, limestone, granite, gneiss, therapeutic muds and others, except for amber) | 5 % |
The size of rent payment rates for the use of subsoil in the case of extraction of other types of minerals, except for hydrocarbons and iron ore, in 2020
| Object of taxation | Rate |
|---|---|
| Ore (metal-bearing (metallic), including ores) minerals: | |
| ferrous (other than iron one), colour and alloying metals (before 23.05.2020 | 5 % |
| ferrous (other than iron one), colour and alloying metals (from 23.05.2020) | 6,25 % |
| uraniferous, and other than uraniferous ores of ferrous, colour and alloying metals | 5 % |
| iron ore (before 23.05.2020) | 8 % |
| iron ore (from 23.05.2020) | 11-12 % |
| Energy minerals | |
| coking coal | 1,5 % |
| energy coal | 0,75 % |
| anthracite | 1 % |
| brown | 1 % |
| Non-energy, non-ore (non-metal-containing (non-metal)) minerals, including quartz sand, groundwaters, fire clay, high-melting clay, limestone, granite, gneiss, therapeutic muds and others, except for amber) | 5 % |
From 23.05.2020, the rate of production royalty for the extraction of ferrous metals (except iron ores), non-ferrous and alloy metals was increased and constituted 6.5%, for the extraction of iron ore — 12%, if the average value of iron ore for the tax (reporting) period is USD 70 or more according to IODEX 58% FE CFR China, officially determined by the world news agency Platts, or 11%, if such average cost was less than USD 70, the rates and conditions for the application of certain adjusting coefficients to production royalty rates also were changed.

During 2023–2024, the rules governing the production royalty for subsoil use related to iron ore extraction remained unchanged.
Since the beginning of 2022, the rules governing the production royalty for subsoil use in relation to iron ore extraction have been amended as follows:
-
►
The tax base is calculated using only the actual selling price, rather than a comparison of the two values. The actual selling price is determined according to the general rules provided for the minerals other than hydrocarbons.
-
►
The production royalty rate for the extraction of iron ore were differenced depending on the average actual selling price determined as the average cost of iron ore according to the Platts IODEX 62% FE CFR China.
Production royalty rates for iron ore mining 2022 - 2024
| Object of taxation | Rate |
|---|---|
| Iron ore, if the average cost of iron ore according to the IODEX 62% FE CFR China index, officially determined by the global information agency Platts, for the tax (reporting) period is: | |
| 100 USD or less | 3.5 % |
| More than 100 USD but does not exceed 200 USD inclusively | 5 % |
| More than 200 USD | 10 % |
Production royalty for subsoil use for the extraction of minerals other than hydrocarbons
Production royalty for the extraction of minerals (other than hydrocarbons) of national importance was distributed between the general funds of the budgets as follows:
-
►
70% was transferred to the general fund of the State Budget of Ukraine.
-
►
25% — to the general fund of the regional budgets/ Kyiv city budget.
-
►
5% — to the general fund of the local government budgets.
Production royalty for the extraction of minerals of local importance was paid to the budget of the local government at the location (place of extraction) of the relevant natural resources in full.
Payment reconciliation
According to the results of the reconciliation of payments for 2024, the amount of state revenues from the production royalty from the extractive companies, according to state authorities, amounted to UAH 50,130,995.74 thousand, and according to the data of the extractive companies it was UAH 50,130,980.90 thousand. The amount of discrepancies between the data of taxpayers and the data of state authorities, according to the results of the initial request, amounted to UAH 2,331,760.61 thousand, and after reconciliation and clarifications, the amount of discrepancies is UAH 14.84 thousand.
According to the results of the reconciliation of payments for 2023, the payments in favour of the state from the production royalty from the extractive companies, according to the state authorities, amounted to UAH 57,990,377.32 thousand, and UAH 57,990,188.66 thousand according to the data of the extractive companies. The discrepancy between the data of the taxpayers and the data of state authorities, according to the results of the initial request, amounted to UAH 6,818,281.82 thousand, and after the reconciliation and clarifications, the discrepancy is UAH 188.66 thousand.
According to the results of the reconciliation of payments for 2022, the amount of state revenues from the production royalty from the extractive companies, according to state authorities, amounted to UAH 81,988,108.94 thousand, and according to the data of the extractive companies it was UAH 81,986,286.60 thousand. The amount of discrepancies between the data of taxpayers and the data of state authorities, according to the results of the initial request, amounted to UAH 3,266.44 thousand, and after reconciliation and clarifications, the amount of discrepancies is UAH 1,822.33 thousand.
Considering the provisions of the Terms of Reference, neither the reconciliation of data on payments in favour of the state nor the analysis of discrepancies was performed for the EITI Report 2021. Instead, payment data were disclosed unilaterally, without reconciliation.
According to the results of the reconciliation of payments for 2020, the amount of state revenues from the production royalty from the extractive companies, according to state authorities, amounted to UAH 48,506,126.71 thousand, and according to the data of the extractive companies it was UAH 48,510,026.58 thousand. The amount of discrepancies between the data of taxpayers and the data of state authorities, according to the results of the initial request, amounted to UAH (215,358.74) thousand, and after reconciliation and clarifications, the amount of discrepancies is UAH (3 899,87) thousand.
According to the results of the reconciliation of payments for 2019, the amount of state revenues from the production royalty from the extractive companies, according to state authorities, amounted to UAH 42,547,316.09 thousand, and according to the data of the extractive companies it was UAH 42,547,471.66 thousand. The amount of discrepancies between the data of taxpayers and the data of state authorities, according to the results of the initial request, amounted to UAH 95,785.95 thousand, and after reconciliation and clarifications, the amount of discrepancies is UAH (155,57) thousand.
According to the results of the reconciliation of payments for 2018, the amount of state revenues from the production royalty from the extractive companies, according to state authorities, amounted to UAH 40,672,021.77 thousand, and according to the data of the extractive companies it was UAH 40,661,323.35 thousand. The amount of discrepancies between the data of taxpayers and the data of state authorities, according to the results of the initial request, amounted to UAH 1,510,741.81 thousand, and after reconciliation and clarifications, the amount of discrepancies is UAH 10 698,41 thousand.
DATA OF REPORTS OF BUSINESS ENTITIES
| Year | Company name | USREOU Code | Code according to the Codifier of administrative-territorial units and territories of territorial communities | Name of the budget program | Special permit for subsoil use | Agreement on the use of subsoil | A mineral that is mined | Budget revenue classification code | Type of payment | Payment currency | Due, thousand | Paid, thousand | Note | |||
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Registration number | Issue date | Counterparty according to the agreement | Registration number | Date of conclusion | ||||||||||||