


payments according to target budgets
Loading...
DATA OF REPORTS OF BUSINESS ENTITIES
| Year | Company name | USREOU Code | Budget revenue classification code | Type of payment | Payment currency | Due, thousand | Paid, thousand | Source |
|---|
Reconciliation of payments
Reconciliation of payments
Loading...
During 2020–2024, the list of material payments underwent changes; in particular, Royalty for transportation and payments by companies under List 1 and List 2 were added to the list of material payments.
In 2024, the list of material payments was as follows:
-
►
Production royalty for extraction of mineral of national importance (BRCC 13030000)
-
►
Value added tax on goods produced in Ukraine (excluding budget VAT refund) (BRCC 14060000 (excluding 14060200))
-
►
Corporate income tax (BRCC 11020000)
-
►
Budget VAT refund (BRCC 14060200)
-
►
Personal income tax (BRCC 11010000)
-
►
Unified social contribution (USC)
-
►
Value added tax on goods imported into Ukraine (BRCC 14070000)
-
►
Land fee from legal entities (BRCC 18010500, 18010600)
-
►
Fee for issuance of special permits for subsoil use and proceeds from the sale of such permits. (BRCC 22012100)
-
►
Dividends and payment of a share of net profit (BRCC 21010100, 21010500)
-
►
Environmental tax (BRCC 19010000)
-
►
Royalty for transportation (BRCC 13080000)
-
►
Reimbursement of Pension Fund expenses for payment and delivery of preferential pensions
Сompleteness of the reconciliation
Сompleteness of the reconciliation in 2024
In 2024, 55 companies, 3 JVAs and 1 PSA (hereinafter referred to as 59 material reporting companies) were identified that were subject to reconciliation of tax and non-tax payments in favour of the state. All reporting companies, according to the data from state authorities, paid a total of UAH 168,977,293.22 thousand (including budget reimbursement of VAT) as material types of payments. As part of the preparation of the EITI Report 2024, information about their payments in favour of the state was received from 51 of the 59 reporting companies.
In order to assess the materiality of the revenues in favour of the state and determine the material types of payments and reporting companies, the requests were formed and sent to the STS, SCS, SGS and PFU. In 2024, all state authorities that are managers of information on the payment of material types of payments in favour of the state provided the required data for the purposes of reconciling tax and other revenues.
Thus, the Independent Administrator reconciled data on state revenues from 51 material companies in the amount of UAH 165,975,379.34 thousand (according to the information provided by state agencies). As a result, the completeness of the reconciliation was 98.22% in terms of state revenues. The total revenues from the reporting companies that did not provide the necessary information for reconciliation is UAH 3,001,913.88 thousand or 1.78%. For comparison, the completeness of the reconciliation of payments in the EITI Report 2023 was 98.67%.
The highest reconciliation completeness rate among the reporting extractive industries was achieved by public sector companies in the metal ore and oil and gas industries (100% and 100%, respectively).
Of the total material revenues to the state from 59 reporting extractive companies in the amount of UAH 168,977,292.22 thousand:
-
►
72.90% of revenues were accounted for by 36 companies that passed the payment reconciliation and whose financial statements for 2024 had been audited, according to the information provided by companies.
-
►
25.32% of revenues were accounted for by 15 companies that passed the payment reconciliation and which did not provide information about whether their financial statements had been audited.
-
►
1.78% of revenues were accounted for by 9 companies that did not pass the payment reconciliation and which did not provide information about an audit.
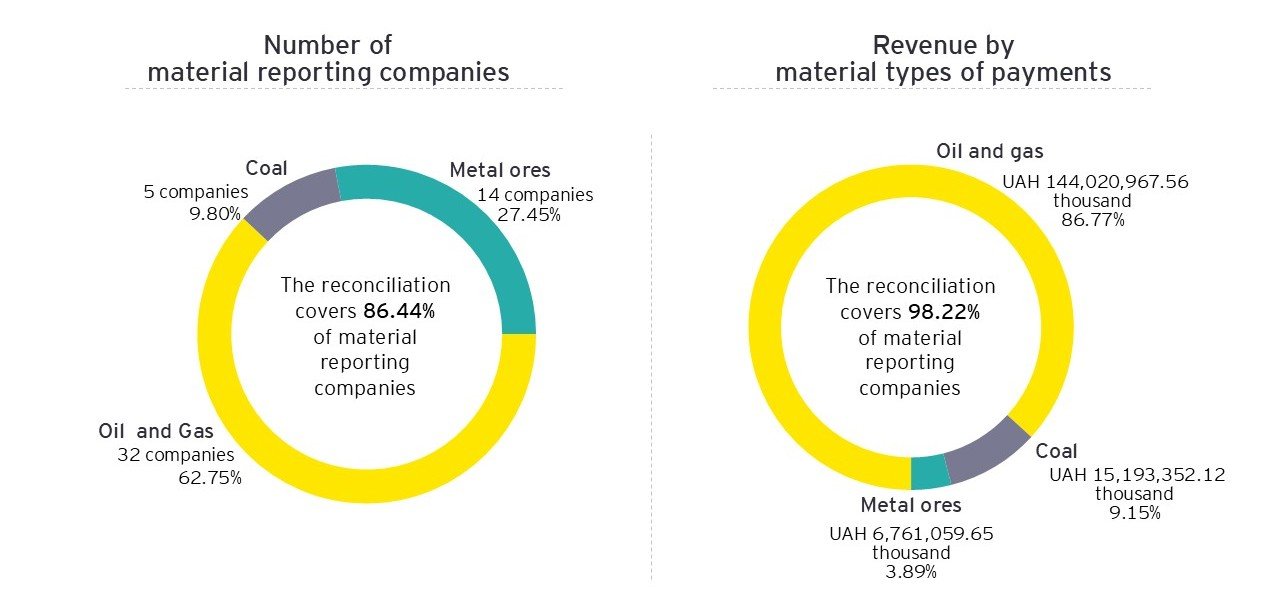 The number of companies and the amount of revenues for material types of payments (including VAT refund from the state budget) for which a reconciliation was conducted in 2024
The stages of assessing the materiality of government revenues and identifying material payment streams and reporting companies covered by the reconciliation of government revenues in the EITI Report for 2024 are illustrated in the figure below.
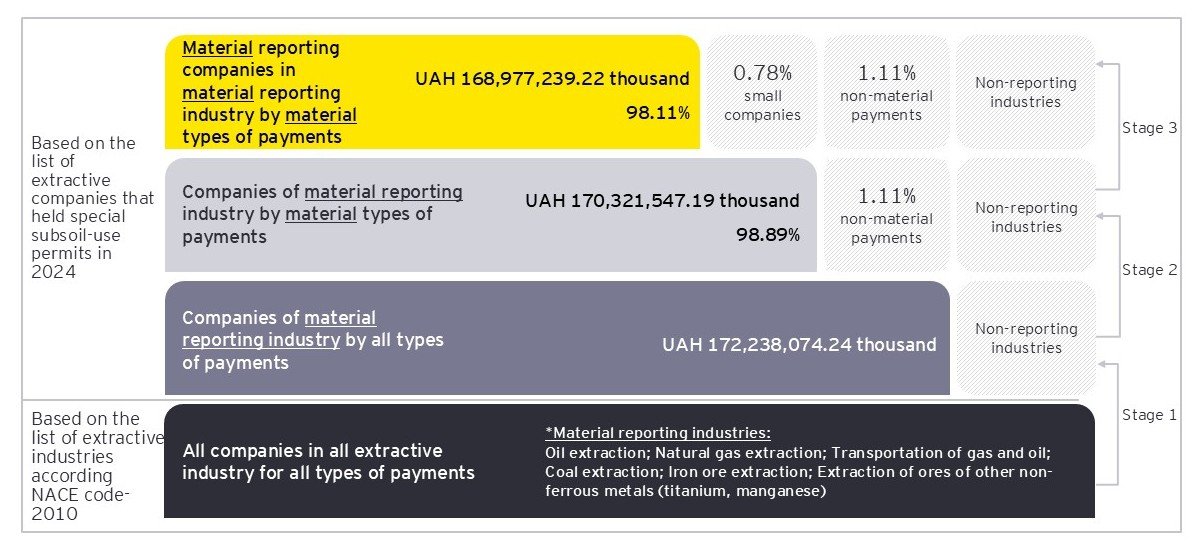 Schematic presentation of the materiality assessment for the purposes of the EITI Report (including VAT refund from the state budget) for 2024
Сompleteness of the reconciliation in 2023
59 companies were identified in 2023 that were subject to reconciliation of tax and non-tax payments in favour of the state. All material reporting companies, according to the data from the state authorities, paid the total of UAH 147,337,171.65 thousand for material types of payments (including VAT refund from the state budget). As part of the preparation of the EITI Report 2023, the information on their payments in favour of the state was received from 53 of 59 material reporting companies.
To assess the materiality of revenues in favour of the state and determine material types of payments and material reporting companies, the requests were formed and sent to the STS, SCS, the Ministry of Economy and the SGS. In 2023, all state authorities that are managers of information on material types of payments in favour of the state provided the necessary data for the purposes of reconciliation of tax and other revenues.
Therefore, the Independent Administrator reconciled data on state revenues from 53 material companies in the amount of UAH 145,371,584.17 thousand (according to information provided by the state authorities). As a result, the completeness of the reconciliation was 98.67% in terms of state revenues. The total amount of revenues from material reporting companies that did not provide the necessary information for reconciliation is UAH 1,965,587.48 thousand or 1.33%.
The highest reconciliation completeness was demonstrated by public sector companies in the metal ore and oil and gas industries (100% and 100%, respectively).
Of the total amount of UAH 147,337,171.65 thousand of material receipts in favour of the state from 59 material reporting extractive companies:
-
►
64.48% of the revenues are accounted for 33 companies that have passed payment reconciliation and which, according to the information provided by them, have their financial statements for 2023 audited
-
►
34.19% of the revenues are accounted for by 20 companies that have passed payment reconciliation and which have not provided information on the audit of their financial statements for 2023
-
►
1.33% of the revenues are accounted for by 6 companies that have not passed payment reconciliation and which have not provided information on the audit of their financial statements for 2023
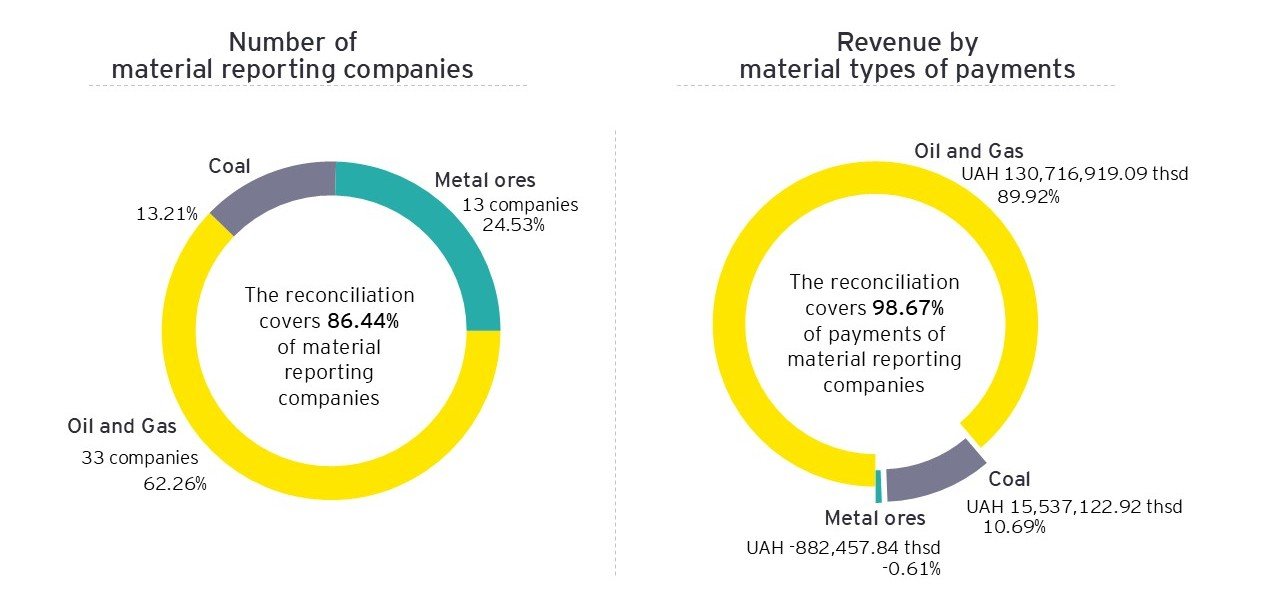 The number of companies and the amount of revenues for material types of payments (including VAT refund from the state budget) for which a reconciliation was conducted in 2023
The stages of assessing the materiality of government revenues and identifying material payment streams and reporting companies covered by the reconciliation of government revenues in the EITI Report for 2023 are illustrated in the figure below.
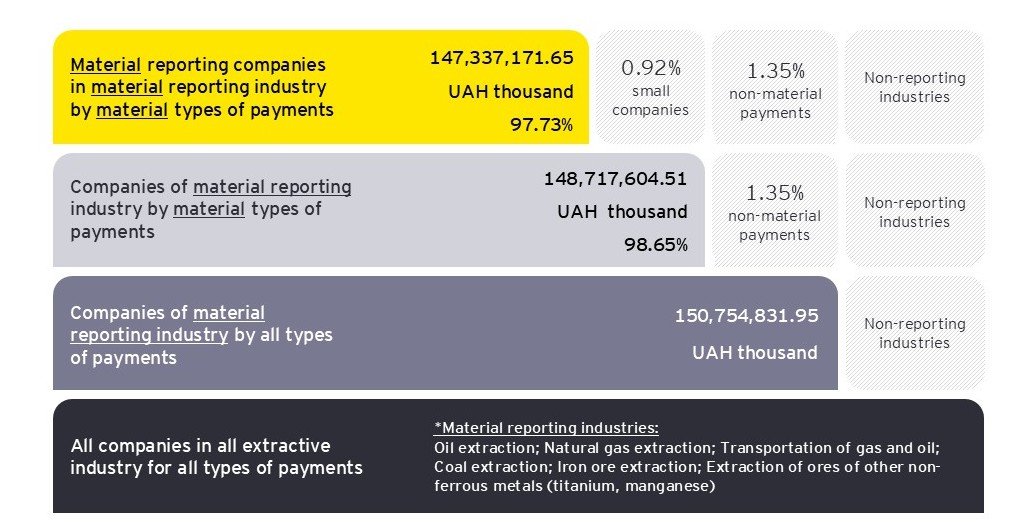 Schematic presentation of the materiality assessment for the purposes of the EITI Report (including VAT refund from the state budget) for 2023
Сompleteness of the reconciliation in 2022
In 2022, 65 companies were identified that were subject to reconciliation of tax and non-tax payments in favour of the state. All material reporting companies, according to the data from the state authorities, paid a total of UAH 185,384,062.65 thousand for material types of payments (including VAT refund from the state budget). As part of the preparation of the EITI Report 2022, information on their payments in favour of the state was received from 59 of the 65 reporting companies.
To assess the materiality of revenues in favour of the state and determine material types of payments and material reporting companies, the requests were formed and sent to the STS, SCS, the Ministry of Economy and the SGS. In 2022, all state authorities that are managers of information on material types of payments in favour of the state provided the necessary data for the purposes of reconciliation of tax and other revenues.
Therefore, the Independent Administrator reconciled data on state revenues from 59 material companies in the amount of UAH 175,281,911.64 thousand (according to information provided by the state authorities). As a result, the completeness of the reconciliation was 94.55% in terms of state revenues. The total amount of revenues from material reporting companies that did not provide the necessary information for reconciliation is UAH 10,102,151.01 thousand or 5.45%.
As no payment reconciliation was conducted for the EITI Report 2021, no comparison can be made in terms of reconciliation completeness. It should be noted that, due to russia’s full-scale invasion of Ukraine, the number of reporting companies decreased compared to 2020. At the same time, for comparison, the completeness of the reconciliation of payments in the EITI Report 2020 was 100%.
The highest reconciliation completeness rate among the reporting extractive industries was achieved by the metal ore mining industry, as all 16 material reporting companies provided information on tax and other payments, which made it possible to reconcile 100% of revenues in favour of the state from companies in this industry. The coal mining industry ranked second, as 9 of the 11 material reporting companies provided information on payments in favour of the state, enabling the reconciliation of 96.69% of revenues. The lowest reconciliation completeness rate was recorded in the oil and gas industry, where 34 of the 38 material reporting companies provided information on payments, which enabled the reconciliation of 93.64% of the total amount of revenues.
Of the total material revenues in favour of the state from 65 material reporting extractive companies in the amount of UAH 185,384,062.65 thousand:
-
►
58.37% of the revenues were accounted for by 34 companies that passed payment reconciliation and which, according to the information provided by them, had their financial statements for 2022 audited;
-
►
36.18% of the revenues were accounted for by 25 companies that passed payment reconciliation and which did not provide information on the audit of their financial statements for 2022;
-
►
5.45% of the revenues were accounted for by 6 companies that did not pass payment reconciliation, and which did not provide information on the audit of their financial statements for 2022.
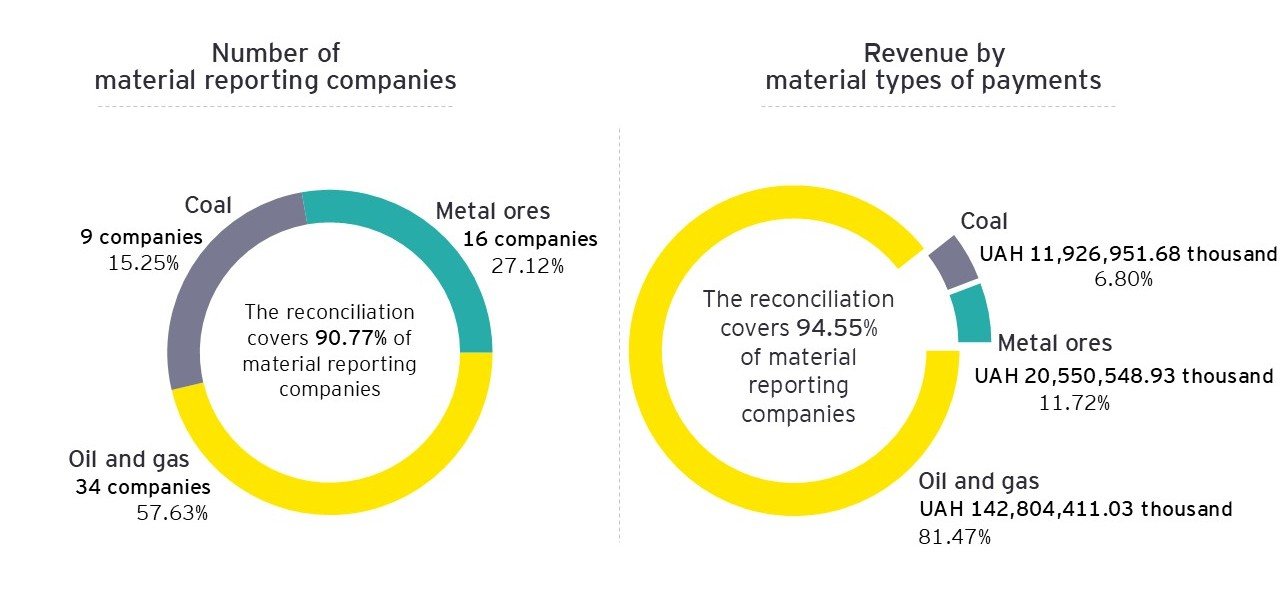 The number of companies and the amount of revenues for material types of payments (including VAT refund from the state budget) for which a reconciliation was conducted in 2022
The stages of assessing the materiality of government revenues and identifying material payment streams and reporting companies covered by the reconciliation of government revenues in the EITI Report for 2022 are illustrated in the figure below.
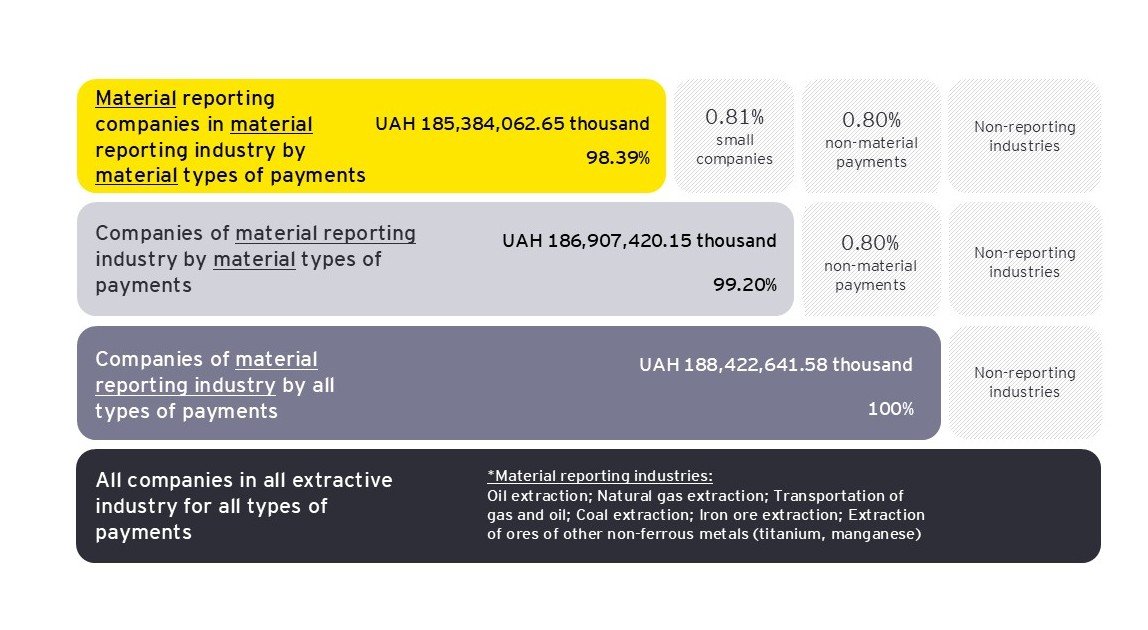 Schematic presentation of the materiality assessment for the purposes of the EITI Report (including VAT refund from the state budget) for 2022
Сompleteness of the reconciliation in 2021
Considering the provisions of the Terms of Reference, neither the reconciliation of data on payments in favour of the state nor the analysis of discrepancies was performed for the EITI Report 2021. Instead, payment data were disclosed unilaterally, without reconciliation.
In 2021, 57 material reporting companies were identified for the purposes of reconciliation of tax and non-tax payments in favour of the state. All material reporting companies, according to data from state authorities, paid a total of UAH 211,508,834.62 thousand in material types of payments (including VAT refunds from the state budget).
As part of the preparation of the EITI Report 2021, reports on payments in favour of the state / consolidated reports on payments in favour of the state were submitted by 27 of the 57 material extractive companies covered by this EITI Report 2021. Information on one additional company was provided through the consolidated report of its parent company.
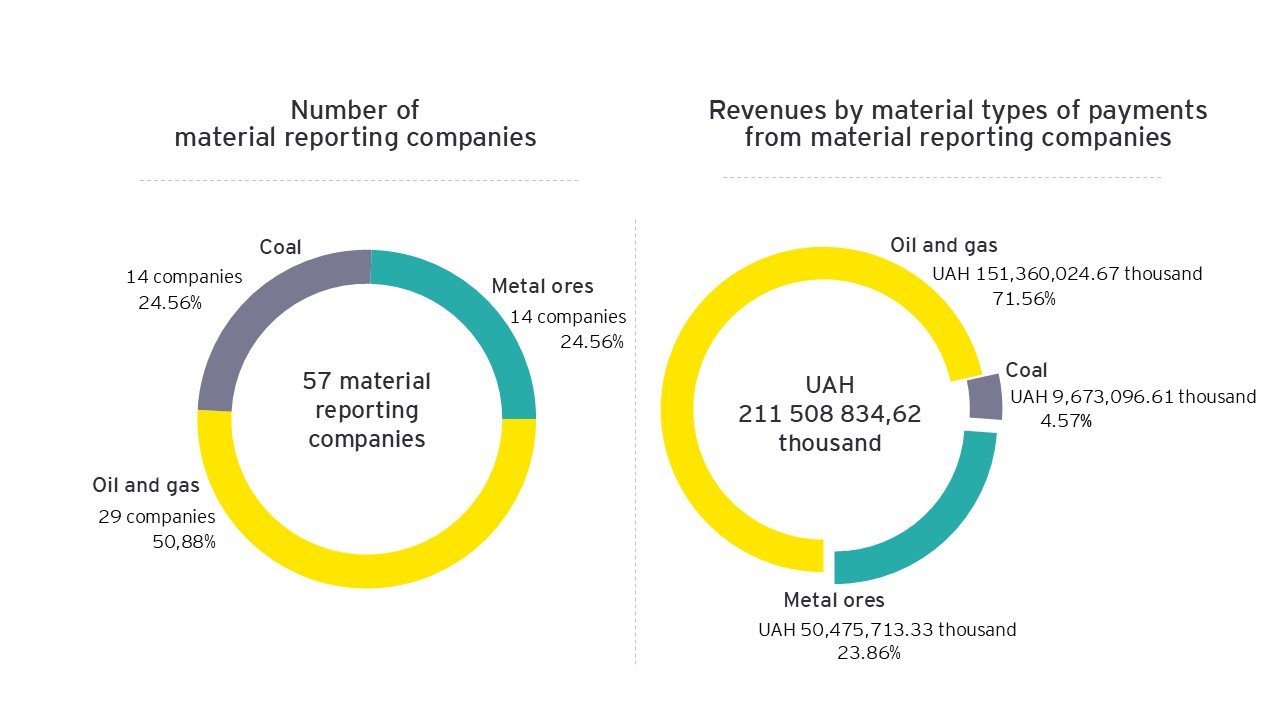 The number of companies and the amount of revenues for material types of payments (including VAT refund from the state budget) for which a reconciliation was conducted in 2021
The stages of assessing the materiality of government revenues and identifying material payment streams and reporting companies covered by the reconciliation of government revenues in the EITI Report for 2021 are illustrated in the figure below.
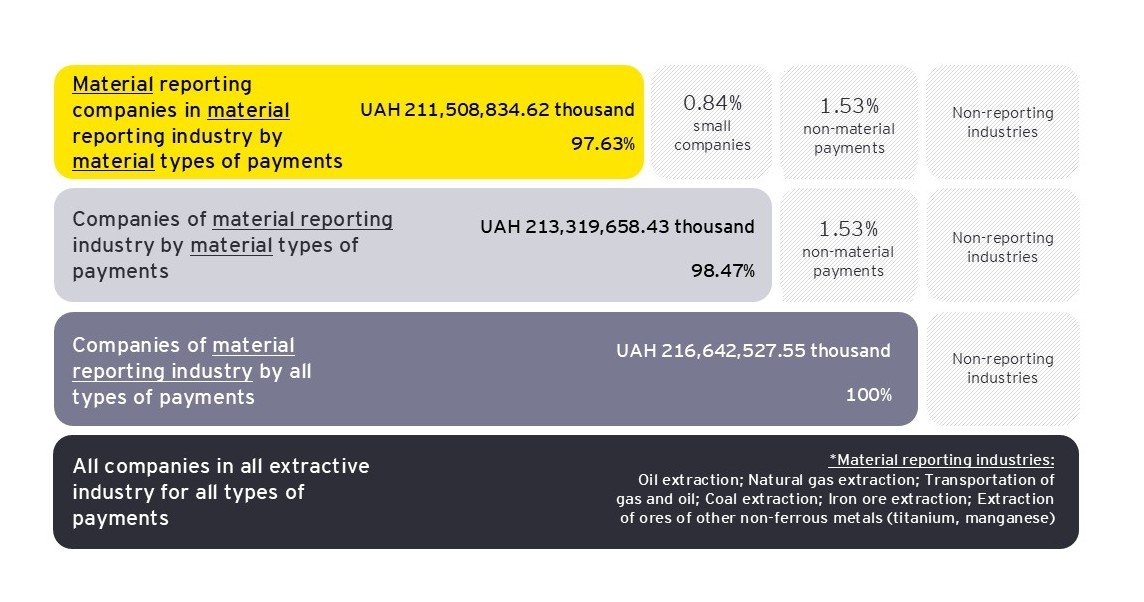 Schematic presentation of the materiality assessment for the purposes of the EITI Report (including VAT refund from the state budget) for 2021
Сompleteness of the reconciliation in 2020
To assess the materiality of revenues in favour of the state and identify material types of payments and material reporting companies, the inquiries were sent to the State Tax Service, State Customs Service, Ministry of Economy and Geology Service.
In 2020, all government agencies that oversee information on material types of payments in favour of the state, provided the necessary data for the purposes of reconciling tax and other revenues. In 2020, 54 material reporting companies were identified that were subject to reconciliation of tax and non-tax payments in favour of the state. According to government agencies, all material reporting companies paid a total of UAH 182,857,572.64 thousand for material types of payments (including budget reimbursement of VAT). In 2020, all material reporting companies identified during the materiality assessment provided their data for the EITI Report 2020.
Thus, the total revenues of UAH 182,857,572.64 thousand received from all 54 material reporting companies in favour of the state have been reconciled, which means 100% completeness of the reconciliation in 2020. For comparison, the completeness of the reconciliation of payments in the EITI Reports 2018 and 2019 was 99.06%.
Of the total UAH 182,857,572.64 thousand material revenues in favour of the state from 54 material reporting companies:
-
►
98.18% of revenues are received from 51 material reporting companies whose payments had been reconciled and whose financial statements for 2020 had been audited, according to the information provided by them;
-
►
1.82% of revenues are received from 3 material reporting companies whose payments had been reconciled but they did not provide information about the audit of their financial statements.
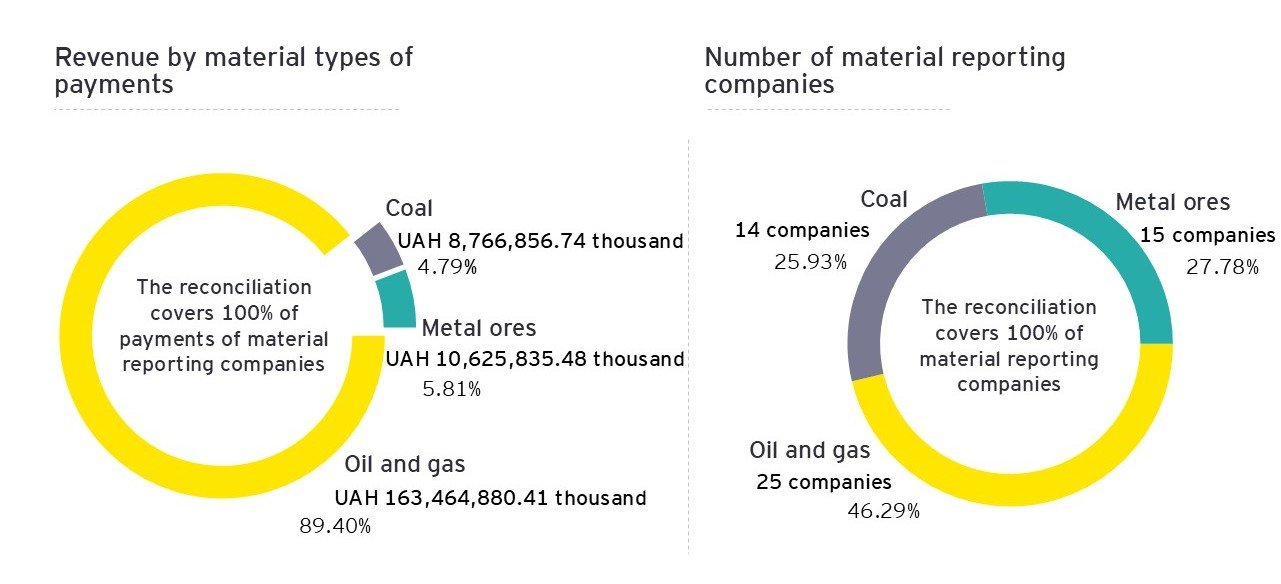 The number of companies and the amount of revenues for material types of payments (including VAT refund from the state budget) for which a reconciliation was conducted in 2020
The stages of assessing the materiality of government revenues and identifying material payment streams and reporting companies covered by the reconciliation of government revenues in the EITI Report for 2020 are illustrated in the figure below.
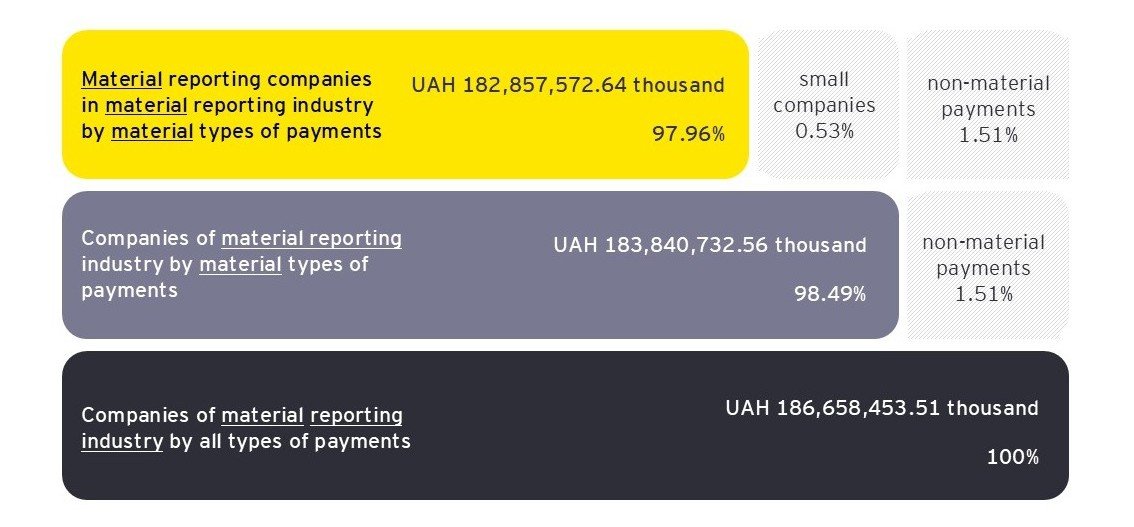 Schematic presentation of the materiality assessment for the purposes of the EITI Report (including VAT refund from the state budget) for 2020
Payment reconciliation data
| Year | Name | USREOU Code | Activity | Materiality of the company | Materiality of payment | Verification | Type of receipt | Payment type | Data of state bodies, thousand hryvnias | Data of mining companies, thousand hryvnias | Difference, thousand hryvnias |
|---|
VAT on goods imported into the customs territory of Ukraine
According to the results of the reconciliation of payments for 2024, the amount of state revenues from VAT on goods imported into the customs territory of Ukraine, from extractive companies, according to state authorities, amounted to UAH 6,700,655.83 thousand, and according to the extractive companies, UAH 6,640,430.30 thousand. The amount of discrepancies between the data of taxpayers and the data of state authorities, according to the results of the initial request, amounted to UAH 346,485.87 thousand, and after reconciliation and clarifications, the amount of discrepancies was UAH 60,255.53 thousand.
According to the results of the reconciliation of payments for 2023, the payments in favour of the state from value added tax on goods imported into the customs territory of Ukraine from extractive companies, according to state authorities, amounted to UAH 7,053,975.84 thousand, and UAH 7,403,072.79 thousand according to extractive companies. The amount of discrepancies between the data of the taxpayers and the data of the state authorities, according to the results of the initial request, amounted to UAH (359,214.74) thousand, and after reconciliation and clarifications, the discrepancies amounted to UAH (349,096.95) thousand.
According to the results of the reconciliation of payments for 2022, the payments in favour of the state from value added tax on goods imported into the customs territory of Ukraine from extractive companies, according to state authorities, amounted to UAH 8,796,363.13 thousand, and UAH 8,742,837.01 thousand according to extractive companies. The amount of discrepancies between the data of the taxpayers and the data of the state authorities, according to the results of the initial request, amounted to UAH 265,245.36 thousand, and after reconciliation and clarifications, the discrepancies amounted to UAH 53,526.12 thousand.
Considering the provisions of the Terms of Reference, neither the reconciliation of data on payments in favour of the state nor the analysis of discrepancies was performed for the EITI Report 2021. Instead, payment data were disclosed unilaterally, without reconciliation.
According to the results of the reconciliation of payments for 2020, the payments in favour of the state from value added tax on goods imported into the customs territory of Ukraine from extractive companies, according to state authorities, amounted to UAH 5,504,649.09 thousand, and UAH 5,517,280.75 thousand according to extractive companies. The amount of discrepancies between the data of the taxpayers and the data of the state authorities, according to the results of the initial request, amounted to UAH 868,575.75 thousand, and after reconciliation and clarifications, the discrepancies amounted to UAH (12,631.67) thousand.
According to the results of the reconciliation of payments for 2019, the payments in favour of the state from value added tax on goods imported into the customs territory of Ukraine from extractive companies, according to state authorities, amounted to UAH 14,982,703.25 thousand, and UAH 14,583,716.53 thousand according to extractive companies. The amount of discrepancies between the data of the taxpayers and the data of the state authorities, according to the results of the initial request, amounted to UAH 1,457,570.34 thousand, and after reconciliation and clarifications, the discrepancies amounted to UAH 398,986.72 thousand.
According to the results of the reconciliation of payments for 2018, the payments in favour of the state from value added tax on goods imported into the customs territory of Ukraine from extractive companies, according to state authorities, amounted to UAH 19,329,341.03 thousand, and UAH 19,302,103.77 thousand according to extractive companies. The amount of discrepancies between the data of the taxpayers and the data of the state authorities, according to the results of the initial request, amounted to UAH 1,166,955.62 thousand, and after reconciliation and clarifications, the discrepancies amounted to UAH 27,237.26 thousand.
VAT on produced goods

In 2024, the VAT electronic administration system was in operation, which provides for opening special payer accounts for accounting of tax amounts, the establishment of the Unified Register of Tax Invoices, the preparation and registration of tax invoices in electronic form, the submission of VAT reports electronically by all VAT payers, etc.
In 2024, a number of special rules applied for the extractive industries companies. They included:
-
►
The import of natural gas into the customs territory of Ukraine by Naftogaz of Ukraine NJSC under the code according to the UCG FEA 2711 21 00 00 was exempted from VAT. This provision will be valid for six months after the end of martial law.
-
►
For PSA, a number of VAT exemptions were provided for the import of goods and services intended for PSA, as well as for the import of commodities extracted in the exclusive (maritime) economic zone of Ukraine. There was also a special mechanism for the formation of a tax credit in multilateral PSAs by the PSA operator and individual investors within the PSA.
In 2024, VAT was paid into the general fund of the State Budget in full. VAT for the extractive industry companies is charged at rates of 20% and 0%, while individual transactions may not be subject to VAT.
According to the results of the reconciliation of payments for 2024, the amount of state revenues from VAT on goods produced in Ukraine (excluding budget reimbursement of VAT) from the extractive companies, according to the state authorities, amounted to UAH 41,394,174.06 thousand, and according to extractive companies it was UAH 41,395,280.84 thousand. The amount of discrepancies between the data of taxpayers and the data of the state authorities, according to the results of the initial request, amounted to UAH 73,004.86 thousand, and after reconciliation and clarifications, the amount of discrepancies amounted to UAH 1,106.78 thousand.
During 2023, the VAT electronic administration system was in operation. The system provides for the creation of special payer accounts for accounting of tax amounts, the Unified Register of Tax Invoices, the preparation and registration of tax invoices in electronic form, the submission of VAT reports in electronic form by all payers, etc.
In 2023, a number of special rules applied to the entities in the extractive industries, including the following:
-
►
The natural gas imported into the customs territory of Ukraine by Naftogaz of Ukraine NJSC under the USCG FEA code 2711 21 00 00 was exempted from VAT. This regulation will be valid for six months after the end of martial law.
-
►
For PSA, a number of VAT exemptions were provided for the import of goods and services intended for the PSA, as well as for the import of products extracted in the exclusive (maritime) economic zone of Ukraine. There was also a special mechanism for the formation of a tax credit in multilateral PSAs by the PSA operator and individual investors under the PSA.
In 2023, VAT was paid into the general fund of the State Budget in full. The VAT for the companies in the extractive industries is charged at rates of 20% and 0%, while specific types of transactions may not be subject to VAT.
According to the results of the reconciliation of payments for 2023, the amount of payments in favour of the state from value-added tax on goods produced in Ukraine (excluding VAT refund from the state budget) from the extractive companies, amounted to UAH 38,187,767.96 thousand according to the state authorities, and UAH 38,160,181.62 thousand according to the extractive companies. The discrepancies between the taxpayers' data and the state authorities' data, according to the results of the initial request, amounted to UAH 62,782.89 thousand, and after the reconciliation and clarifications, the amount of discrepancies decreased to UAH 27,586.34 thousand.
VAT for the extractive industry companies is charged at rates of 20% and 0%, while individual transactions may not be subject to VAT.
Imports of products from the extractive industries are subject to VAT at the standard rate of 20%. Exports of goods were subject to a zero rate of VAT.
Until 2022, transactions involving the supply of coal and/or coal beneficiation products under UCG FEA headings 2701, 2702 and 2704 00 within the customs territory of Ukraine were temporarily exempt from VAT. At the same time, taxpayers could waive the application of this exemption or suspend its application for one or more reporting periods by submitting an application.
Negative VAT balances were subject to reimbursement to taxpayers. As the metal ore mining industry is export-oriented, unlike the oil and gas industry, companies operating in this industry typically generate significant amounts of VAT subject to reimbursement from the state budget.
In order to fulfil the obligations related to the unbundling of natural gas transmission activities and to ensure the functioning of the gas transmission system operator undertaken by Ukraine pursuant to the Law of Ukraine “On Ratification of the Protocol on the Accession of Ukraine to the Treaty Establishing the Energy Community”, a number of special rules regarding the VAT treatment of asset transfers and natural gas loans, temporarily introduced on 11 December 2019, continued to apply in 2022.
In 2022, the provisions on VAT reimbursement were temporarily suspended from March to July 2022 as a result of russia’s military aggression against Ukraine and the introduction of martial law. Following the resumption of VAT reimbursement, significant amounts of VAT subject to reimbursement from the state budget were again typical for companies in the metal ore mining industry.
In 2022, an electronic VAT administration system was in place. The system provides for the setting up of special VAT accounts to keep track of the VAT amounts, the Unified Tax Invoices Registry, drafting and registration of VAT invoices in electronic form, filing VAT statements electronically by all taxpayers etc.
In 2024, a number of special rules applied for the extractive industries companies. They included:
-
►
For PSA, a number of VAT exemptions were provided for the import of goods and services intended for the PSA, as well as for the import of products extracted in the exclusive (maritime) economic zone of Ukraine. There was also a special mechanism for the formation of a tax credit in multilateral PSAs by the PSA operator and individual investors under the PSA.
-
►
From 25 November 2022, the import of natural gas into the customs territory of Ukraine by Naftogaz of Ukraine NJSC under the UCG FEA code 2711 21 00 00 was exempted from VAT. This provision will remain in force for six months after the end of martial law.
-
►
Until 31 December 2022, the import into the customs territory of Ukraine by Naftogaz of Ukraine NJSC of natural gas imported into Ukraine by pipeline transport during 2014–2015 under an obligation to submit an additional customs declaration, for which no additional declarations had been processed by the customs authorities as of 19 August 2022, was exempted from VAT. This provision entered into force on 19 August 2022.
-
►
Temporarily, for the reporting periods of 2022, and for the purposes of implementing the measures provided for by the Law of Ukraine “On Measures Aimed at Overcoming Crisis Phenomena and Ensuring Financial Stability in the Natural Gas Market”, participants in the debt settlement procedure, including Naftogaz of Ukraine NJSC, Ukrtransgaz JSC and the GTSOU, participating in the settlement of debts of natural gas market entities financed from state budget expenditures, did not adjust VAT previously included in tax credits and/or tax liabilities and did not alter the composition of tax liabilities and/or tax credits by the amount of such settlements. This provision entered into force on 19 August 2022.
According to the results of the reconciliation of payments for 2022, the amount of state revenues from VAT on goods produced in Ukraine (excluding budget reimbursement of VAT) from the extractive companies, according to the state authorities, amounted to UAH 40,587,883.21 thousand, and according to extractive companies it was UAH 40,587,883.21 thousand. The amount of discrepancies between the data of taxpayers and the data of the state authorities, according to the results of the initial request, amounted to UAH 411,873.84 thousand, and after reconciliation and clarifications, the amount of discrepancies amounted to UAH 16,055.48 thousand.
In 2021, an electronic VAT administration system was in place. The system provides for the setting up of special VAT accounts to keep track of the VAT amounts, the Unified Tax Invoices Registry, drafting and registration of VAT invoices in electronic form, filing VAT statements electronically by all taxpayers etc. In 2021, VAT was paid to the General Fund of the State Budget in full.
Considering the provisions of the Terms of Reference, neither the reconciliation of data on payments in favour of the state nor the analysis of discrepancies was performed for the EITI Report 2021. Instead, payment data were disclosed unilaterally, without reconciliation.
In 2020, an electronic VAT administration system was in place. The system provides for the setting up of special VAT accounts to keep track of the VAT amounts, the Unified Tax Invoices Registry, drafting and registration of VAT invoices in electronic form, filing VAT statements electronically by all taxpayers etc. In 2020, VAT was paid to the General Fund of the State Budget in full.
According to the results of the reconciliation of payments for 2020, the amount of state revenues from VAT on goods produced in Ukraine (excluding budget reimbursement of VAT) from the extractive companies, according to the state authorities, amounted to UAH 40,786,284.76 thousand, and according to extractive companies it was UAH 40,786,352.98 thousand. The amount of discrepancies between the data of taxpayers and the data of the state authorities, according to the results of the initial request, amounted to UAH 525,980.43 thousand, and after reconciliation and clarifications, the amount of discrepancies amounted to UAH (68.21) thousand.
According to the results of the reconciliation of payments for 2019, the amount of state revenues from VAT on goods produced in Ukraine (excluding budget reimbursement of VAT) from the extractive companies, according to the state authorities, amounted to UAH 36,592,308.74 thousand, and according to extractive companies it was UAH 36,685,708.94 thousand. The amount of discrepancies between the data of taxpayers and the data of the state authorities, according to the results of the initial request, amounted to UAH 5,082,152.65 thousand, and after reconciliation and clarifications, the amount of discrepancies amounted to UAH (93,400.20) thousand.
According to the results of the reconciliation of payments for 2018, the amount of state revenues from VAT on goods produced in Ukraine (excluding budget reimbursement of VAT) from the extractive companies, according to the state authorities, amounted to UAH 44,819,136.89 thousand, and according to extractive companies it was UAH 44,771,174.72 thousand. The amount of discrepancies between the data of taxpayers and the data of the state authorities, according to the results of the initial request, amounted to UAH 5,431,364.46 thousand, and after reconciliation and clarifications, the amount of discrepancies amounted to UAH 47,962.17 thousand.
Unified social contribution

The Unified Social Contribution was accrued and paid in 2021–2024 in accordance with the following provisions:
-
►
the single rate for USC calculation by the employer was 22% of the tax base, with the exception of special calculation rates for people with disabilities, which have not changed since 2014 (8.41%, 5.3% and 5.5%);
-
►
the maximum amount of monthly income from which the USC is paid is equal to 15 minimum wage established by law (UAH 106,500 UAH from 01.01.2024).
The funds paid as USC as well as the funds paid as a result of application of relevant financial sanctions related to the untimely payment/non-payment of the USC were not subject to inclusion in the State Budget of Ukraine or the budgets of other levels but were distributed for the needs of national social insurance.
In 2021 - 2024, the paid USC was distributed in three directions (with some exceptions provided for by the relevant CMU resolution), as presented in the figure below.
-
►
Mandatory state pension insurance - 85.62%
-
►
Mandatory state social insurance in. connection with temporary disability - 9.57%
-
►
Mandatory state social insurance in case-of unemployment - 4.81%
According to the results of the reconciliation of payments for 2024, the amount of the state revenues from the unified social contribution from the extractive companies, according to the state authorities, amounted to UAH 10,174,137.58 thousand, and according to the extractive companies, it was UAH 10,174,638.77 thousand. The amount of discrepancies between the data of taxpayers and the data of the state authorities, according to the results of the initial request, amounted to UAH 917,041.18 thousand, and after reconciliation and clarifications, the amount of discrepancies amounted to UAH (501.19) thousand.
According to the results of the reconciliation of payments for 2023, the amount of payments in favour of the state from the unified social contribution from extractive companies, according to state authorities, amounted to UAH 9,152,795.94 thousand, and UAH 9,152,970.77 thousand according to the data of the extractive companies. The discrepancies between the data of the taxpayers and the data of the state bodies, according to the results of the initial request, amounted to UAH 11,772.83 thousand, and after reconciliation and clarifications, the discrepancies amounted to UAH (174.83) thousand.
According to the results of the reconciliation of payments for 2022, the amount of the state revenues from the unified social contribution from the extractive companies, according to the state authorities, amounted to UAH 9,410,520.49 thousand, and according to the extractive companies, it was UAH 9,410,655.63 thousand. The amount of discrepancies between the data of taxpayers and the data of the state authorities, according to the results of the initial request, amounted to UAH (160,396.71) thousand, and after reconciliation and clarifications, the amount of discrepancies amounted to UAH (135.14) thousand.
Considering the provisions of the Terms of Reference, neither the reconciliation of data on payments in favour of the state nor the analysis of discrepancies was performed for the EITI Report 2021. Instead, payment data were disclosed unilaterally, without reconciliation.
The Unified Social Contribution was calculated in 2020 with the following specifics:
-
►
the single rate for the calculation of the USC by the employer was 22% of the tax base, with the exception of special rates for people with disabilities, which remained unchanged from 2014 (8.41%, 5.3% and 5.5%)
-
►
the maximum monthly income from which the USC is paid was set at 15 minimum wages established by law (UAH 70,845 until 01.09.2020 and UAH 75,000 from 01.09.2020).
According to the results of the reconciliation of payments for 2020, the amount of the state revenues from the unified social contribution from the extractive companies, according to the state authorities, amounted to UAH 9,862,966.78 thousand, and according to the extractive companies, it was UAH 9,868,800.21 thousand. The amount of discrepancies between the data of taxpayers and the data of the state authorities, according to the results of the initial request, amounted to UAH 1,554,248.31 thousand, and after reconciliation and clarifications, the amount of discrepancies amounted to UAH (5,833,43) thousand.
According to the results of the reconciliation of payments for 2019, the amount of the state revenues from the unified social contribution from the extractive companies, according to the state authorities, amounted to UAH 9,245,351.24 thousand, and according to the extractive companies, it was UAH 9,269,477.06 thousand. The amount of discrepancies between the data of taxpayers and the data of the state authorities, according to the results of the initial request, amounted to UAH 794,057.34 thousand, and after reconciliation and clarifications, the amount of discrepancies amounted to UAH (24,125.82) thousand.
According to the results of the reconciliation of payments for 2018, the amount of the state revenues from the unified social contribution from the extractive companies, according to the state authorities, amounted to UAH 7,929,403.37 thousand, and according to the extractive companies, it was UAH 7,948,394.80 thousand. The amount of discrepancies between the data of taxpayers and the data of the state authorities, according to the results of the initial request, amounted to UAH 805,750.85 thousand, and after reconciliation and clarifications, the amount of discrepancies amounted to UAH (18,991.43) thousand.
DATA FROM REPORTING ENTITIES
| Year | Company name | USREOU Code | Budget revenue classification code | Type of payment | Payment currency | Due, thousand | Paid, thousand | Source |
|---|
Personal income tax

The object and basis of taxation was the total (monthly) income of individuals. The Personal Income Tax Department dealt with the tax at the rate of 18%. Mining companies withheld and paid personal income tax on wages and other compensation payments to their employees on a general basis.
During 2023–2024, temporary rules regarding the distribution of PIT (other than that paid in the territory of Kyiv and other than PIT from taxation of income in the form of cash benefits, cash rewards and other payments received by military personnel, police officers and ordinary and commanding personnel):
-
►
21% - to the general fund of the State Budget;
-
►
64% — to the general fund of the budgets of rural, settlement, urban territorial communities;
-
►
15% — to the general fund of regional budgets
Personal Income Tax paid in the territory of Kyiv City was distributed according to the rules established by the Budget Code:
-
►
60% - was credited to the general fund of the State Budget;
-
►
40% — to the general fund of the budget of Kyiv City.
As a temporary exception to the provisions of the Budget Code, separate distribution rules were in effect for PIT on income in the form of cash benefits, cash rewards, and other payments received by military personnel, police officers, and rank-and-file and command personnel from 01.01.2024 to 31.12.2024.
As a temporary exception to the provisions of the Budget Code, personal income tax paid on income in the form of cash benefits, cash rewards and other payments received by militarypersonnel, police officers and rank-and-file and command personnel from 01.10.2023 to 31.12.2023 was distributed as follows: the part of this personal income tax which is categorised as the general fund revenues of the relevant local budgets was credited in full to the special fund of the State Budget of Ukraine and was directed in the following proportions in the following public authorities.
-
►
50% — to the Administration of the State Service for Special Communications and Information Protection of Ukraine for the procurement of special equipment and machinery.
-
►
50% — to the Ministry of Defence of Ukraine for the procurement of artillery systems.
During 2021–2022, in accordance with the provisions of the Budget Code, 25% of the PIT paid was allocated to the State Budget, while the remaining 75% was distributed among local budgets of different levels. PIT paid in the territory of Kyiv City was distributed as follows: 60% was allocated to the State Budget and 40% to the budget of Kyiv City.
According to the results of the reconciliation of payments for 2024, the amount of state revenues from the personal income tax and levy from the extractive companies, according to state authorities, amounted to UAH 10,435,759.78 thousand, and according to the extractive companies – UAH 10,434,058.39 thousand. The total discrepancies between the data of taxpayers and the data of state authorities, according to the results of the initial request, amounted to UAH 5,388.62 thousand. After reconciliation and clarifications, the amount of discrepancies amounted to UAH 456.31.
According to the results of the reconciliation of payments for 2023, the revenues in favour of the state from the personal income tax from extractive companies, according to the state authorities, amounted to UAH 9,172,625.46 thousand, and according the to extractive companies – UAH 9,171,972.52 thousand. The discrepancy between the data of taxpayers and the data of state authorities, according to the results of the initial request, amounted to UAH 271,458.24 thousand, and after the reconciliation and clarifications, the amount of discrepancy amounted to UAH 652.94 thousand.
According to the results of the reconciliation of payments for 2022, the revenues in favour of the state from the personal income tax from extractive companies, according to the state authorities, amounted to UAH 9,691,668.71 thousand, and according the to extractive companies – UAH 9,691,308.11 thousand. The discrepancy between the data of taxpayers and the data of state authorities, according to the results of the initial request, amounted to UAH (135,245.91) thousand, and after the reconciliation and clarifications, the amount of discrepancy amounted to UAH 360.61 thousand.
Considering the provisions of the Terms of Reference, neither the reconciliation of data on payments in favour of the state nor the analysis of discrepancies was performed for the EITI Report 2021. Instead, payment data were disclosed unilaterally, without reconciliation.
According to the results of the reconciliation of payments for 2020, the revenues in favour of the state from the personal income tax from extractive companies, according to the state authorities, amounted to UAH 10,027,367.23 thousand, and according the to extractive companies – UAH 10,007,011.86 thousand. The discrepancy between the data of taxpayers and the data of state authorities, according to the results of the initial request, amounted to UAH 525,904.61 thousand, and after the reconciliation and clarifications, the amount of discrepancy amounted to UAH 20,355.37 thousand.
According to the results of the reconciliation of payments for 2019, the revenues in favour of the state from the personal income tax from extractive companies, according to the state authorities, amounted to UAH 9,330,071.50 thousand, and according the to extractive companies – UAH 9,029,184.72 thousand. The discrepancy between the data of taxpayers and the data of state authorities, according to the results of the initial request, amounted to UAH 3,098,136.73 thousand, and after the reconciliation and clarifications, the amount of discrepancy amounted to UAH 300,886.78 thousand.
According to the results of the reconciliation of payments for 2018, the revenues in favour of the state from the personal income tax from extractive companies, according to the state authorities, amounted to UAH 7,928,227.87 thousand, and according the to extractive companies – UAH 7,930,119.97 thousand. The discrepancy between the data of taxpayers and the data of state authorities, according to the results of the initial request, amounted to UAH 2,376,047.72 thousand, and after the reconciliation and clarifications, the amount of discrepancy amounted to UAH (1,892.11) thousand.
Environmental tax
The object and base of taxation were volumes and types of pollutants. The Tax Code provided for the application of a tax rate for the disposal of waste that falls under the definition of "low-hazardous non-toxic waste from the mining industry" at a level significantly lower than for the rest of the low-hazardous waste of group IV.
Environmental tax rates remained unchanged in 2023–2024 A gradual increase in the tax rate on discharges of certain pollutants into water bodies is envisaged over the period 2022–2025: (in 2022, the rate was 30%, in 2023, the rate was 60%, in 2024, the rate was 90%, in 2025, it will reach 100%).
During 2023-2024, no environmental tax was charged or paid for the taxable objects located:
-
►
in the territories where hostilities are on-going or were conducted or in territories temporarily occupied by russian armed forces.
-
►
at the location of stationary sources of pollution, for the generation of radioactive waste and temporary storage of radioactive waste on land contaminated with explosives.
In 2023-2024, the environmental tax rate for carbon dioxide emissions from stationary installations was 30.00 UAH per 1 ton. The environmental tax is not paid for emissions not exceeding 500 tons per year. At the same time, the environmental tax is not paid for emissions that do not exceed 500 tons per year. In 2023, there was no greenhouse gas emissions trading system in Ukraine.
Since 2024, the environmental tax levied on emissions of carbon dioxide into the atmosphere by stationary sources of pollution was fully credited to the special fund of the State Budget and directed to the State Fund for Decarbonization and Energy Efficiency transformations.
In 2022, the environmental tax rate for mining waste amounted to UAH 0.54 per tonne of waste, while for other taxpayers it amounted to UAH 5.50 per tonne. Thus, mining enterprises paid an environmental tax on the disposal of low-hazard industrial waste that was nearly ten times lower than that paid by enterprises in other industries.
In 2022, the environmental tax rate for carbon dioxide emissions was UAH 30.00 per tonne. The environmental tax is not paid for emissions not exceeding 500 tonnes per year.
In 2022, the environmental tax rates increased as follows:
-
►
for carbon dioxide emissions, from UAH 10 to UAH 30 per tonne (an increase of 200%);
-
►
for emissions of certain pollutants into the atmosphere, the rates of which depend on the hazard class of the pollutant (by 5%);
-
►
for discharges of certain pollutants into water bodies (by 700%) and for waste disposal, the rates of which depend on the hazard class and hazard level of waste (by 10%).
-
►
A gradual increase in the tax rate on discharges of certain pollutants into water bodies is envisaged over the period 2022–2025. In 2022, the rate was 30% of the established rate.
In 2022, no environmental tax was charged or paid for taxable objects located in territories where hostilities were ongoing or had been conducted, or in territories temporarily occupied by russian armed forces. The list of territories where hostilities are ongoing or have been conducted, or which are temporarily occupied by russian armed forces, is determined by the CMU.
In accordance with the provisions of the Budget Code, the environmental tax paid was generally distributed as follows (except for the environmental tax charged on carbon dioxide emissions from stationary sources of pollution, which in 2022 was credited in full to the general fund of the State Budget):
-
►
State Budget – 45%;
-
►
Local self-government budgets – 25%;
-
►
Regional budgets and the budget of Kyiv City – 30%.
In 2021, the environmental tax rate for mining waste amounted to UAH 0.49 per tonne of waste, while for other taxpayers it amounted to UAH 5.00 per tonne. Thus, mining enterprises paid an environmental tax on the disposal of low-hazard industrial waste that was nearly ten times lower than that paid by enterprises in other industries.
In 2021, the environmental tax rate for carbon dioxide emissions was UAH 10.00 per tonne. The environmental tax is not paid for emissions not exceeding 500 tonnes per year.
In 2022, compared to 2021, environmental tax rates increased for carbon dioxide emissions (from UAH 10 to UAH 30 per tonne, or by 200%), for emissions of certain pollutants into the atmosphere, the rates of which depend on the hazard class of the pollutant (by 5%), for discharges of certain pollutants into water bodies (by 700%), and for waste disposal, the rates of which depend on the hazard class and hazard level of waste (by 10%). A gradual increase in the tax rate on discharges of certain pollutants into water bodies is envisaged over the period 2022–2025 (in 2022, the rate was 30% of the established rate).
In accordance with the provisions of the Budget Code, 45% of the environmental tax paid was generally credited to the State Budget, while the remaining 55% was distributed among the special funds of local budgets at different levels (except for the environmental tax charged on carbon dioxide emissions from stationary sources of pollution, which in 2021 was credited in full to the general fund of the State Budget).
In 2020, environmental tax rates have not changed compared to the previous year.
The rate for mining waste was 0.49 UAH/t of waste, while for the rest of the payers it was 5.00 UAH/t.
In 2020, the carbon tax rate constituted UAH 10.00 per tonne.440 At the same time, the environmental tax was not charged for the volumes of emission not exceeding 500 tonnes per year.
According to the provisions of the Budget Code, as a general rule, 45% of the environmental tax paid was transferred to the State budget, and the rest 55% was distributed among special funds of local budgets of different levels (except for the environmental tax levied on emissions of carbon dioxide into the atmosphere by stationary sources of pollution, which was included in the general fund of the State budget in full since 2020).
According to the results of the reconciliation of payments for 2024, the amount of state revenues from the environmental tax paid by the extractive companies, according to the state authorities, amounted to UAH 760,903.01 thousand, and according to extractive companies, UAH 737,909.11 thousand. The amount of discrepancies between the data of taxpayers and the data of the state authorities, according to the results of the initial request, amounted to UAH 23,760.17 thousand, and after reconciliation and clarifications, the amount of discrepancies amounted to UAH 22,993.90 thousand.
According to the results of the reconciliation of payments for 2023, the revenues in favour of the state from the environmental tax from the extractive companies, according to state authorities, amounted to UAH 586,173.39 thousand, and according to extractive companies, UAH 566,096.82 thousand. The discrepancies between the data of the taxpayers and the data of state authorities, according to the results of the initial request, amounted to UAH 21,017.49 thousand, and after reconciliation and clarifications, the discrepancies amounted to UAH 20,076.57 thousand.
According to the results of the reconciliation of payments for 2022, the revenues in favour of the state from the environmental tax from the extractive companies, according to state authorities, amounted to UAH 810,003.44 thousand, and according to extractive companies, UAH 787,191.86 thousand. The discrepancies between the data of the taxpayers and the data of state authorities, according to the results of the initial request, amounted to UAH 25,338.13 thousand, and after reconciliation and clarifications, the discrepancies amounted to UAH 22,811.58 thousand.
Considering the provisions of the Terms of Reference, neither the reconciliation of data on payments in favour of the state nor the analysis of discrepancies was performed for the EITI Report 2021. Instead, payment data were disclosed unilaterally, without reconciliation.
According to the results of the reconciliation of payments for 2020, the revenues in favour of the state from the environmental tax from the extractive companies, according to state authorities, amounted to UAH 970,140.40 thousand, and according to extractive companies, UAH 953,714.94 thousand. The discrepancies between the data of the taxpayers and the data of state authorities, according to the results of the initial request, amounted to UAH 15,911.28 thousand, and after reconciliation and clarifications, the discrepancies amounted to UAH 16,425.47 thousand.
According to the results of the reconciliation of payments for 2019, the revenues in favour of the state from the environmental tax from the extractive companies, according to state authorities, amounted to UAH 978,828.41 thousand, and according to extractive companies, UAH 961,753.93 thousand. The discrepancies between the data of the taxpayers and the data of state authorities, according to the results of the initial request, amounted to UAH 18,094.26 thousand, and after reconciliation and clarifications, the discrepancies amounted to UAH 17,074.48 thousand.
According to the results of the reconciliation of payments for 2018, the revenues in favour of the state from the environmental tax from the extractive companies, according to state authorities, amounted to UAH 785,822.36 thousand, and according to extractive companies, UAH 772,060.48 thousand. The discrepancies between the data of the taxpayers and the data of state authorities, according to the results of the initial request, amounted to UAH 15,661.67 thousand, and after reconciliation and clarifications, the discrepancies amounted to UAH 13,761.88 thousand.
DATA FROM REPORTING ENTITIES
| Year | Company name | USREOU Code | Code according to the Codifier of administrative-territorial units and territories of territorial communities | Name of the budget program | Special permit for subsoil use | Agreement on the use of subsoil | A mineral that is mined | Budget revenue classification code | Type of payment | Payment currency | Due, thousand | Paid, thousand | Note | |||
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Registration number | Issue date | Counterparty according to the agreement | Registration number | Date of conclusion | ||||||||||||
Corporate income tax
In 2020-2024, corporate income tax was paid at the rate of 18%.
In 2023-2024, the object of corporate income tax for the majority of extractive companies was determined as the financial result before taxes (profit or loss), determined in the financial statements of the company and prepared in accordance with national accounting regulations (standards) or International Financial Reporting Standards, subject to a number of adjustments established by the Tax Code.
The Tax Code does not establish special rules for determining taxable income for extractive companies and for the persons carrying out activities in the extractive industry under the PSA.
Corporate income tax under the PSA was calculated according to the special rules. In particular, the object of taxation under the PSA was calculated based on the value of profitable products, reduced by the amount of the USC and the costs that are not reimbursed (not subject to reimbursement) by compensatory products. Other income of the investor was not subject to corporate income tax. Investor paid corporate income tax on income from other activities not related to the PSA implementation under the general rules.
In 2023 - 2024, the Budget Code provided that 90% of the income tax paid by private enterprises is directed to the general fund of the State Budget of Ukraine, 10% to the general fund of regional budgets and the budget of the city of Kyiv. At the same time, the income tax paid by state-owned enterprises was fully included in the general fund of the State Budget of Ukraine
According to the results of the reconciliation of payments for 2024, the amount of revenue of the state from corporate income tax paid by the extractive companies, according to state authorities, amounted to UAH 30,632,824.97 thousand, and according to extractive companies it was UAH 30,632,417.91 thousand. The amount of discrepancies between the data of taxpayers and the data of the state authorities, according to the results of the initial request, amounted to UAH (130,951,021.44) thousand, and after reconciliation and clarifications, the amount of discrepancies amounted to UAH 407.06 thousand.
According to the results of the reconciliation of payments for 2023, the amount of payments in favour of the state from corporate income tax from extractive companies, according to the state authorities, amounted to UAH 31,640,399.19 thousand, and UAH 31,640,396.35 thousand according to the extractive companies. The discrepancy between the data of the taxpayers and the data of the state authorities, according to the results of the initial request, amounted to UAH (6,584,657.19) thousand, and after reconciliation and clarifications, the discrepancy amounted to UAH 2.84 thousand.
According to the results of the reconciliation of payments for 2022, the amount of revenue of the state from corporate income tax paid by the extractive companies, according to state authorities, amounted to UAH 25,255,812.76 thousand, and according to extractive companies it was UAH 25,255,437.73 thousand. The amount of discrepancies between the data of taxpayers and the data of the state authorities, according to the results of the initial request, amounted to UAH 77,688.64 thousand, and after reconciliation and clarifications, the amount of discrepancies amounted to UAH 375.03 thousand.
Considering the provisions of the Terms of Reference, neither the reconciliation of data on payments in favour of the state nor the analysis of discrepancies was performed for the EITI Report 2021. Instead, payment data were disclosed unilaterally, without reconciliation.
According to the results of the reconciliation of payments for 2020, the amount of revenue of the state from corporate income tax paid by the extractive companies, according to state authorities, amounted to UAH 40,119,991.86 thousand, and according to extractive companies it was UAH 40,118,340.19 thousand. The amount of discrepancies between the data of taxpayers and the data of the state authorities, according to the results of the initial request, amounted to UAH 26,125.57 thousand, and after reconciliation and clarifications, the amount of discrepancies amounted to UAH 1,651.67 thousand.
According to the results of the reconciliation of payments for 2019, the amount of revenue of the state from corporate income tax paid by the extractive companies, according to state authorities, amounted to UAH 38,831,737.58 thousand, and according to extractive companies it was UAH 38,830,631.70 thousand. The amount of discrepancies between the data of taxpayers and the data of the state authorities, according to the results of the initial request, amounted to UAH 1,668,911.83 thousand, and after reconciliation and clarifications, the amount of discrepancies amounted to UAH 1,105.89 thousand.
According to the results of the reconciliation of payments for 2018, the amount of revenue of the state from corporate income tax paid by the extractive companies, according to state authorities, amounted to UAH 40,698,710.49 thousand, and according to extractive companies it was UAH 40,697,306.75 thousand. The amount of discrepancies between the data of taxpayers and the data of the state authorities, according to the results of the initial request, amounted to UAH 259,087.12 thousand, and after reconciliation and clarifications, the amount of discrepancies amounted to UAH 1,403.74 thousand.
DATA FROM REPORTING ENTITIES
| Year | Company name | USREOU Code | Budget revenue classification code | Type of payment | Payment currency | Due, thousand | Paid, thousand | Source |
|---|
VAT refund from the state budget
According to the results of the reconciliation of payments for 2024, the amount of budget reimbursement of value added tax to mining companies, according to the state authorities, was UAH (16,485,066.35) thousand, and according to the data of mining companies UAH (16,485,062.62) thousand. The amount of discrepancies between the data of taxpayers and the data of the state authorities, according to the results of the initial request, was UAH (3.73) thousand and remained the same after the reconciliation.
According to the results of the reconciliation of payments for 2023, the amount of budget reimbursement to extractive companies, according to state bodies, was UAH (14,648,811.84) thousand, and according to the data of the extractive companies, it was UAH (14,648,005.23) thousand. The amount of discrepancies between the data of the taxpayers and the data of the state authorities, according to the results of the initial request, was UAH (806.61) thousand, and after the reconciliation and clarifications, the amount of the discrepancies did not change.
According to the results of the reconciliation of payments for 2022, the amount of budget reimbursement of value added tax to mining companies, according to state authorities, amounted to UAH (8,773,981.18) thousand, and according to extractive companies, UAH (8,773,981.62) thousand. The discrepancies between the data of the taxpayers and the data of state authorities, according to the results of the initial request, amounted to UAH (93,204.56) thousand, and after reconciliation and clarifications, the discrepancies amounted to UAH 0.44 thousand.
Considering the provisions of the Terms of Reference, neither the reconciliation of data on payments in favour of the state nor the analysis of discrepancies was performed for the EITI Report 2021. Instead, payment data were disclosed unilaterally, without reconciliation.
According to the results of the reconciliation of payments for 2020, the amount of budget reimbursement of value added tax to mining companies, according to state authorities, amounted to UAH (14,846,490.11) thousand, and according to extractive companies, UAH (14,846,489.68) thousand. The discrepancies between the data of the taxpayers and the data of state authorities, according to the results of the initial request, amounted to UAH (9,511,305.76) thousand, and after reconciliation and clarifications, the discrepancies amounted to UAH (0.43) thousand.
According to the results of the reconciliation of payments for 2019, the amount of budget reimbursement of value added tax to mining companies, according to state authorities, amounted to UAH (16,157,566.53) thousand, and according to extractive companies, UAH (16,157,566.18) thousand. The discrepancies between the data of the taxpayers and the data of state authorities, according to the results of the initial request, amounted to UAH (6,885,166.72) thousand, and after reconciliation and clarifications, the discrepancies amounted to UAH (0.35) thousand.
According to the results of the reconciliation of payments for 2018, the amount of budget reimbursement of value added tax to mining companies, according to state authorities, amounted to UAH (11,376,594.24) thousand, and according to extractive companies, UAH (11,376,593.99) thousand. The discrepancies between the data of the taxpayers and the data of state authorities, according to the results of the initial request, amounted to UAH (4,223,127.17) thousand, and after reconciliation and clarifications, the discrepancies amounted to UAH (0.25) thousand.
Dividends and payment of a share of net profit
Dividends on the state share and part of the net profit on the state share were also equated to tax liabilities and directed entirely to the general fund of the state budget.
According to the results of the reconciliation of payments for 2024, the amount of the state revenues from dividends and payment of a share of net profit from the extractive companies, according to the state authorities, amounted to UAH 23,547,692.47 thousand, and according to extractive companies, it was UAH 23,547,692.42 thousand. The amount of discrepancies between the taxpayers’ data and the state authority’s data, according to the results of the initial request, amounted to UAH 0.05 thousand, and after the reconciliation and clarifications, the amount did not change.
According to the results of the reconciliation of payments for 2023, the revenues in favour of the state from dividends and payment of a share of net profit from extractive companies, according to state authorities, amounted to UAH 1,490,568.59 thousand, and according to extractive companies, UAH 1,490,568.57 thousand. The discrepancies between the data of taxpayers and the data of the state bodies, according to the results of the initial request, amounted to UAH 965,730.24 thousand, and after reconciliation and clarifications, the discrepancies amounted to UAH 0.02 thousand.
According to the results of the reconciliation of payments for 2022, the revenues in favour of the state from dividends and payment of a share of net profit from extractive companies, according to state authorities, amounted to UAH 4,873,589.12thousand, and according to extractive companies, UAH 4,873,589.30 thousand. The discrepancies between the data of taxpayers and the data of the state bodies, according to the results of the initial request, amounted to UAH 749,999.82 thousand, and after reconciliation and clarifications, the discrepancies amounted to UAH (0.18) thousand.
Considering the provisions of the Terms of Reference, neither the reconciliation of data on payments in favour of the state nor the analysis of discrepancies was performed for the EITI Report 2021. Instead, payment data were disclosed unilaterally, without reconciliation.
According to the results of the reconciliation of payments for 2020, the amount of budget reimbursement to extractive companies, according to state bodies, was UAH 39,677,419.49 thousand, and according to the data of the extractive companies, it was UAH 39,677,419.68 thousand. The amount of discrepancies between the data of the taxpayers and the data of the state authorities, according to the results of the initial request, was UAH (0.19) thousand. Clarifications were not carried out.
According to the results of the reconciliation of payments for 2019, the revenues in favour of the state from dividends and payment of a share of net profit from extractive companies, according to state authorities, amounted to UAH 20,787,324.44 thousand, and according to extractive companies, UAH 20,787,324.17 thousand. The discrepancies between the data of taxpayers and the data of the state bodies, according to the results of the initial request, amounted to UAH 12,251,935.34 thousand, and after reconciliation and clarifications, the discrepancies amounted to UAH 0.27 thousand.
According to the results of the reconciliation of payments for 2018, the revenues in favour of the state from dividends and payment of a share of net profit from extractive companies, according to state authorities, amounted to UAH 28,946,680.32 thousand, and according to extractive companies, UAH 29,846,673.02 thousand. The discrepancies between the data of taxpayers and the data of the state bodies, according to the results of the initial request, amounted to UAH 28,613,492.57 thousand, and after reconciliation and clarifications, the discrepancies amounted to UAH (899,992.70) thousand.
Fee for issuance of special permits for subsoil use and proceeds from the sale of such permits
The fee is charged for issuing special permits for subsoil use. The amount of the fee for issuing a special permit for subsoil use is determined based on the results of an auction (electronic bidding). If a special permit for subsoil use is issued without an auction, a fee of 100% of the initial selling price of the relevant special permit for subsoil use at the auction is charged.
If a special permit for subsoil use is issued without an auction for the purpose of fulfilling a production sharing agreement, a fee of 1% of the initial selling price of such a special permit for subsoil use at the auction is charged.
The initial selling price at an auction (electronic bidding) of a special permit for subsoil use is determined in accordance with the methodology approved by the CMU.
The fee was fully paid to the general fund of the State Budget.
According to the results of the reconciliation of payments for 2024, the amount of the stat revenues from the fee for issuance of special permits for subsoil use and proceeds from the sale of such permits from extractive companies, according to the state authorities, amounted to UAH 2,561,089.27 thousand, and according to the extractive companies, it was UAH 2,561,089.26 thousand. The amount of discrepancies between the data of taxpayers and the data of the state authorities, according to the results of the initial request, amounted to UAH 1,290,517.66 thousand, and after reconciliation and clarifications, the amount of discrepancies was UAH 0.01 thousand.
According to the results of the reconciliation of payments for 2023, the revenues in favour of the state in the form of the fee for the issuance of special permits for subsoil use and proceeds from the sale of such permits from extractive companies, according to the state authorities, amounted to UAH 1,813,163.17 thousand, and UAH 1,813,163.18 thousand according to the extractive companies. The discrepancies between the data of the taxpayers and the data of the state bodies, according to the results of the initial request, amounted to UAH 1,791,255.37 thousand, and after reconciliation and clarifications, the discrepancies amounted to UAH - 0.01 thousand.
According to the results of the reconciliation of payments for 2022, the revenues in favour of the state in the form of the fee for the issuance of special permits for subsoil use and proceeds from the sale of such permits from extractive companies, amounted to UAH 121,954.53 thousand according to both the state authorities and the extractive companies. The discrepancies between the data of taxpayers and the data of the state authorities, according to the results of the initial request, amounted to UAH 89,671.79 thousand, and after reconciliation and clarifications, no discrepancies were identified.
Considering the provisions of the Terms of Reference, neither the reconciliation of data on payments in favour of the state nor the analysis of discrepancies was performed for the EITI Report 2021. Instead, payment data were disclosed unilaterally, without reconciliation.
According to the results of the reconciliation of payments for 2020, the revenues in favour of the state in the form of the fee for the issuance of special permits for subsoil use and proceeds from the sale of such permits from extractive companies, amounted to UAH 733,637.30 thousand according to both the state authorities and the extractive companies. The discrepancies between the data of taxpayers and the data of the state authorities, according to the results of the initial request, amounted to UAH 730,458.44 thousand, and after reconciliation and clarifications, no discrepancies were identified.
According to the results of the reconciliation of payments for 2019, the revenues in favour of the state in the form of the fee for the issuance of special permits for subsoil use and proceeds from the sale of such permits from extractive companies, according to the state authorities, amounted to UAH 431,413.62 thousand, and UAH 431,416.22 thousand according to the extractive companies. The discrepancies between the data of the taxpayers and the data of the state bodies, according to the results of the initial request, amounted to UAH 431,411.28 thousand, and after reconciliation and clarifications, the discrepancies amounted to UAH 2.60 thousand.
According to the results of the reconciliation of payments for 2018, the revenues in favour of the state in the form of the fee for the issuance of special permits for subsoil use and proceeds from the sale of such permits from extractive companies, according to the state authorities, amounted to UAH 583,182.39 thousand, and UAH 583,182.38 thousand according to the extractive companies. The discrepancies between the data of the taxpayers and the data of the state bodies, according to the results of the initial request, amounted to UAH 582,131.77 thousand, and after reconciliation and clarifications, the discrepancies amounted to UAH 0.01 thousand.
Production royalty

Since 2015, the production royalty is a state-wide tax that is paid for the use of subsoil for the extraction of minerals; for using the subsoil for purposes not related to the extraction of minerals; for using the radio frequency resource of Ukraine; for special use of water; for special use of forest resources; for the transportation of oil and petroleum products by main oil pipelines and petroleum product pipelines, transit transportation of natural gas and ammonia by pipelines through the territory of Ukraine.

The taxable object was the volume of commodity products of the mining enterprise - extracted minerals (mineral raw materials) (hereinafter referred to as minerals) in the respective tax period, the type of which was established by the conditions for mineral raw materials of the subsoil object (site). The Tax Code also determines the cases when extracted minerals are not included in the taxable object for the purposes of charging production royalty.
The tax base was the value of the volume of mineral resources extracted during the reporting period, calculated separately for each type of mineral commodity (mineral raw material) and for each subsoil area based on the standard delivery terms (finished products warehouse of the mining enterprise).
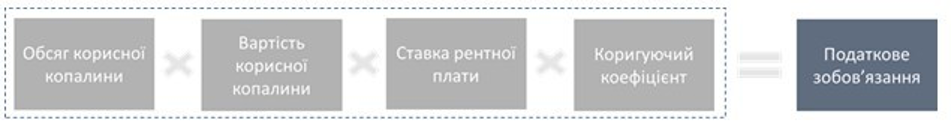
To calculate the tax liability, taxpayers were required to determine the following key parameters for the relevant reporting period: the volume of mineral commodities extracted, the value of such production, the applicable tax rate, and the adjustment coefficient.
Production Royalty calculator
The Production Royalty Calculator is an online tool designed to estimate royalty payments and the carbon footprint associated with mineral production.
Enter the required data to calculate estimated royalty payments and see how these revenues are distributed across different levels of government. The tool also automatically estimates the carbon footprint associated with the extraction of the specified volume of mineral commodities.
Production Royalty calculator
Loading...

The temporary rules for calculating the value of natural gas for the purposes of calculating the production royalty, introduced during the martial law, continued to apply in 2024.
-
►
Before the ban on the export of natural gas outside the customs territory of Ukraine is lifted, the calculation of the cost of natural gas is tied to the prices on the domestic market using the maximum of three values, which were published by the Ministry of Economy on its website by the 10th day of the month following the reporting period.
-
►
The rule regarding the payment of production royalty only for sold gas also continued to apply.
-
►
For natural gas sold by Naftogaz of Ukraine NJSC to form a natural gas resource for household consumers and heat energy producers, the value was the price specified in the natural gas purchase and sale agreements between the production royalty payer and Naftogaz of Ukraine NJSC in the reporting period. Starting 01.12.2024, the actual sale price of natural gas was converted into US dollars at the arithmetic average official exchange rate of the National Bank of Ukraine for the tax (reporting) period.
-
►
For oil and condensate: The Ministry of Economy calculated the average cost of one barrel of Ural oil according to the information from an international agency (UralsMediterranean and UralsRotterdam quotes), converted into UAH per ton at the rate of the National Bank of Ukraine as of the 1st day of the month following the tax (reporting) period (and such cost was published on the official website of the Ministry of Economy).
When carrying out controlled transactions in the cases specified by the Tax Code, the actual selling price should have been not less than the price determined at the arm's length rule.
The temporary rules for calculating the value of natural gas for the purposes of calculating the production royalty, introduced during the martial law, continued to apply in 2023.
For natural gas:
In 2023, the temporary rules for calculating the value of natural gas for the purposes of calculating the rent for the use of subsoil, introduced as a result of martial law, continued to apply:
► In 2023, temporary rules for calculating the value of natural gas for the purposes of calculating the production royalty, which were introduced due to the martial law, continued to apply:
► Until the ban on the export of natural gas out of the customs territory of Ukraine is lifted, the calculation of the value of natural gas will be tied to the prices in the domestic market using the bigger of the following as a factor:
► the weighted average price in the contracts of Naftogaz of Ukraine NJSC concluded for purchasing natural gas of own production on the organized commodity markets.
► the weighted average selling price for natural gas according to the results of trading on organized commodity markets excluding VAT, in UAH per 1000 cubic meters, in the month preceding the reporting month, excluding Naftogaz of Ukraine NJSC and the enterprises in whose authorized capital Naftogaz of Ukraine NJSC has a share of 50% or more.
► the arithmetic mean of the average UA VTP Gas price for the following month.
► The Ministry of Economy publishes the specified indicators on its website by the 10th day of the month following the reporting period.
► The rule for payment of production royalty only for the gas sold also continued to apply.
For natural gas sold by Naftogaz of Ukraine NJSC to form a natural gas resource for household consumers and heat energy producers, the value was the price specified in the natural gas purchase and sale agreements between the production royalty payer and Naftogaz of Ukraine NJSC in the reporting period.
For oil and condensate: The Ministry of Economy calculated the average value of one barrel of Urals according to information from an international agency (UralsMediterranean and UralsRotterdam quotes), converted into UAH per ton at the NBU exchange rate as of the 1st day of the month following the tax (reporting) period (these indicators was published on the official website of the Ministry of Economy).
When carrying out controlled transactions in the cases specified by the Tax Code, the actual selling price should have been not less than the price determined at the arm's length rule.
The tax base for the production royalty for subsoil use for the extraction of hydrocarbons was the value of commodities, namely minerals extracted during the reporting period, calculated according to special rules that changed several times during 2022:
-
1.
For natural gas:
Until March 2022, the Ministry of Economy calculated the average customs value of imported natural gas established during its customs clearance upon importation into Ukraine in the tax period. This value was published on the official website of the Ministry of Economy.
► In March 2022, following the introduction of martial law, the procedure for determining the value of natural gas for the purposes of calculating the production royalty was amended and the production royalty rates were increased. The value of natural gas was to be determined as the arithmetic mean of: the average customs value of imported natural gas established during its customs clearance upon importation into Ukraine in the tax period; and the arithmetic mean of natural gas price quotations for the reporting month, namely Front Month Settlement Prices at the Dutch gas hub TTF, according to information from the European Energy Exchange (EEX), established during the calendar month preceding the tax (reporting) period and calculated by the Ministry of Economy per 1,000 cubic meters in US dollars and in the national currency of Ukraine, excluding VAT, using the arithmetic average official exchange rate of the National Bank of Ukraine for the tax (reporting) period.
Linking the calculation of the production royalty to global gas prices, together with the introduction of differentiated production royalty rates depending on the selling price, increased the tax burden on extractive companies.
► In April 2022, the payment of production royalty only for natural gas sold was temporarily introduced.
► Subsequently, in order to stabilize and reduce the tax burden on production royalty payers for subsoil use for natural gas extraction, temporary rules were introduced. Until the ban on the export of natural gas outside the customs territory of Ukraine is lifted, the calculation of the value of natural gas extracted from 1 August 2022 was tied to prices on the domestic market using the highest of the following values:
- the weighted average price under the contracts of Naftogaz of Ukraine NJSC concluded for the purchase of natural gas of its own production on organized commodity markets;
- the weighted average selling price for natural gas based on the results of trading on organized commodity markets, excluding VAT, in UAH per 1,000 cubic meters, in the month preceding the reporting month, excluding Naftogaz of Ukraine NJSC and enterprises in which Naftogaz of Ukraine NJSC holds 50% or more of the authorized capital;
- the arithmetic mean of the average UA VTP Gas price for the following month.The Ministry of Economy publishes these indicators on its website by the 10th day of the month following the reporting period.
-
2.
For natural gas sold
Natural gas (of any origin) from deposits at a depth of up to 5000 m
Natural gas (of any origin) from deposits at a depth of up to 5000 m Naftogaz of Ukraine NJSC to form a natural gas resource for household consumers and heat energy producers, the value was the price specified in the natural gas purchase and sale agreements between the production royalty payer and Naftogaz of Ukraine NJSC in the reporting period.
-
3.
For oil and condensate: The Ministry of Economy calculated the average value of one barrel of Urals oil according to information from an international agency, based on Urals Mediterranean and Urals Rotterdam quotations, converted into UAH per tonne at the exchange rate of the National Bank of Ukraine as of the first day of the month following the tax (reporting) period. This value was published on the official website of the Ministry of Economy.
When carrying out controlled transactions in the cases specified by the Tax Code, the actual selling price of the relevant commodity of a mining enterprise, namely the extracted mineral or mineral raw material, could not be lower than the price determined according to the arm’s length principle.
The production royalty rates for subsoil use for the extraction of minerals were established by the Tax Code. In March 2022, a mechanism of differentiated production royalty for natural gas was introduced, under which production royalty rates depended on the selling price of natural gas, thereby increasing the tax burden on extractive companies. At the same time, stabilization of the production royalty rates was introduced: the State guarantees that the new production royalty rates cannot be increased until March 2032.
In 2021, the tax base for the production royalty for the use of subsoil for the extraction of hydrocarbons was the value of commodities, namely minerals extracted during the reporting period, calculated according to special rules.
-
►
For natural gas: The Ministry of Economy calculated the average customs value of imported natural gas established during its customs clearance upon importation into Ukraine in the tax period. This value was published on the official website of the Ministry of Economy.
-
►
For natural gas sold by Naftogaz of Ukraine NJSC: To form a natural gas resource for household consumers and heat energy producers, the value was the price specified in the natural gas purchase and sale agreements between the production royalty payer and Naftogaz of Ukraine NJSC in the reporting period.
-
►
For oil and condensate: The Ministry of Economy calculated the average value of one barrel of Urals oil according to information from an international agency (Urals Mediterranean and Urals Rotterdam quotations), converted into UAH per tonne at the exchange rate of the National Bank of Ukraine as of the 1st day of the month following the tax (reporting) period. This value was published on the official website of the Ministry of Economy.
-
►
When carrying out controlled transactions in the cases specified by the Tax Code, the actual selling price of the relevant commodity product of a mining enterprise, namely the extracted mineral (mineral raw material), could not be lower than the price determined in accordance with the arm’s length principle.
The rates of production royalty for the subsoil use for hydrocarbons
The production royalty rates for the use of subsoil for the extraction of minerals were established by the Tax Code.
Royalty rates for subsoil use in hydrocarbon production in 2024
| Object of taxation | Tax rate |
|---|---|
| Oil | |
| from deposits at a depth of up to 5000 m | 31% |
| from deposits at a depth of more than 5000 m | 16% |
| extracted under PSA | 2% |
| Condensate | |
| from deposits at a depth of up to 5000 m | 31% |
| from deposits at a depth of more than 5000 m | 16% |
| extracted under PSA | 2% |
| Natural gas (of any origin) | |
| from deposits at a depth of up to 5000 m | 14,5 %-65% (before 30.11.2024) 29 %-65% (starting 01.12.2024) |
| from deposits at a depth of more than 5000 m | 7%-31% (before 30.11.2024) 14%-31% (starting 01.12.2024) |
| from deposits in subsoil areas (fields) within the continental shelf and/or exclusive (maritime) economic zone of Ukraine | 11% |
| extracted under JVA | 70% |
| extracted under PSA | 1,25% |
| from new wells from deposits at a depth of up to 5000 m | 6%-36% (before 30.11.2024) 12%-36% (starting 01.12.2024) |
| from new wells from deposits at a depth of more than 5000 m | 3%-18% (before 30.11.2024) 6%-18% (starting 01.12.2024) |
In 2023, a mechanism of differentiated production royalty for natural gas was in place, according to which the rates of production royalty depended on the sales price. At the same time, stabilization of production royalty rates continued: the State guarantees that the new production royalty rates cannot increase until March 2032.
Royalty rates for subsoil use in hydrocarbon production in 2023
| Object of taxation | Rate |
|---|---|
| Oil | |
| from deposits at a depth of up to 5000 m | 31% |
| from deposits at a depth of more than 5000 m | 16% |
| extracted under PSA | 2% |
| Condensate | |
| from deposits at a depth of up to 5000 m | 31% |
| from deposits at a depth of more than 5000 m | 16% |
| extracted under PSA | 2% |
| Natural gas (of any origin) | |
| from deposits at a depth of up to 5000 m | 14.5%-65% |
| from deposits at a depth of more than 5000 m | 7%-31% |
| from deposits in subsoil areas (fields) within the continental shelf and/or exclusive (maritime) economic zone of Ukraine | 11% |
| extracted under JVA | 70% |
| extracted under PSA | 1.25% |
| from new wells from deposits at a depth of up to 5000 m | 6%-36% |
| from new wells from deposits at a depth of more than 5000 m | 3%-18% |
For natural gas, in most cases, a differentiated production royalty applied, depending on its selling price.
From 01.12.2024, a law came into force abolishing the reduced rate for the cases where the actual selling price of natural gas for the reporting period is USD 150 or less for 1000 cubic meters.
Actual natural gas production royalty rates in 2024 for the cases where the rate varied depending on the USD equivalent of the actual selling price. Since the price was more than USD 150 but less than USD 400, the rates remained stable throughout 2024.
Natural gas production royalty rates in 2024 subject to the actual selling price of natural gas in 2024
| Month, 2024 | Actual sales price determined by the Ministry of Economy, UAH per 1000 cubic meters | Equivalent to the actual sale price, determined by the Ministry of Economy in USD | from deposits at a depth of up to 5000 m | from deposits at a depth of more than 5000 m | from new wells from deposits at a depth of up to 5000 m | from new wells from deposits at a depth of more than 5000 m |
|---|---|---|---|---|---|---|
| January | 12,738.16 | 339.12 | 29% | 14% | 12% | 6% |
| February | 12,180.30 | 320.12 | 29% | 14% | 12% | 6% |
| March | 11,621.27 | 298.00 | 29% | 14% | 12% | 6% |
| April | 11,124.26 | 281.52 | 29% | 14% | 12% | 6% |
| May | 12,460.08 | 307.66 | 29% | 14% | 12% | 6% |
| June | 12,563.31 | 310.56 | 29% | 14% | 12% | 6% |
| July | 12,699.09 | 309.69 | 29% | 14% | 12% | 6% |
| August | 12,994.71 | 315.48 | 29% | 14% | 12% | 6% |
| September | 14,500.00 | 351.77 | 29% | 14% | 12% | 6% |
| October | 14,405.82 | 349.49 | 29% | 14% | 12% | 6% |
| November | 14,945.69 | 359.31 | 29% | 14% | 12% | 6% |
| December | 15,287.63 | 363.74 | 29% | 14% | 12% | 6% |
When calculating the production royalty, adjusting coefficients (from 0.01 to 0.97) were used depending on the type of raw material and the conditions of its extraction.
-
►
PSA. The rates of fees for subsoil use or production royalty were determined in the PSA, but they could not be lower than those established by Section IX of the Tax Code at the time of conclusion of the PSA.
In 2024, special production royalty rates continued to apply:
- For oil and condensate, the production royalty for the extraction of minerals was calculated at a rate of 2% of the value of the mining enterprise's commodity products.
- For natural gas, the production royalty for the extraction of minerals was calculated at a rate of 1.25% of the value of the mining enterprise's commodity products.
-
►
For legal entities that meet the established criteria for state ownership, a special rate was provided for charging tax on the additional volumes of hydrocarbon raw materials extracted as a result of the implementation of existing or new investment projects that provide for the increase in hydrocarbon raw material production in the amount of 2% of the value of additional extraction of the relevant hydrocarbon raw materials at specified sites and wells.
The procedure for selecting and approving such new investment projects/programs, as well as the procedure for monitoring their implementation, are determined by the CMU upon submission by the Ministry of Economy. The list of subsoil areas and/or subsoil area objects where new investment projects are implemented is determined by the Ministry of Energy.
Actual rates applied to the volumes of natural gas extracted during 2023, which were determined depending on the USD equivalent of the actual sales price in the domestic market (the rates specified in the table do not apply to the cases where the production royalty was calculated and paid for the gas extracted from deposits in subsoil areas (fields) within the continental shelf and/or exclusive (maritime) economic zone of Ukraine, natural gas extracted during under JVAs or PSAs, since in these cases the rate remained unchanged and did not depend on the actual sales price).
Natural gas production royalty rates in 2024 subject to the actual selling price of natural gas in 2023
| Month, 2023 | Actual sales price determined by the Ministry of Economy, UAH per 1000 cubic meters | Equivalent to the actual sale price, determined by the Ministry of Economy in USD | from deposits at a depth of up to 5000 m | from deposits at a depth of more than 5000 m | from new wells from deposits at a depth of up to 5000 m | from new wells from deposits at a depth of more than 5000 m |
|---|---|---|---|---|---|---|
| January | 23,723.43 | 648.74 | 65% | 31% | 36% | 18% |
| February | 20,727.73 | 566.82 | 65% | 31% | 36% | 18% |
| March | 18,680.83 | 510.84 | 65% | 31% | 36% | 18% |
| April | 14,382.34 | 393.30 | 29% | 14% | 12% | 6% |
| May | 11,163.77 | 305.28 | 29% | 14% | 12% | 6% |
| June | 10,742.81 | 293.77 | 29% | 14% | 12% | 6% |
| July | 10,833.33 | 296.25 | 29% | 14% | 12% | 6% |
| August | 12,500.00 | 341.82 | 29% | 14% | 12% | 6% |
| September | 14,849.72 | 406.08 | 65% | 31% | 36% | 18% |
| October | 15,196.24 | 418.85 | 65% | 31% | 36% | 18% |
| November | 14,380.68 | 395.58 | 29% | 14% | 12% | 6% |
| December | 13,595.70 | 357.76 | 29% | 14% | 12% | 6% |
When calculating the production royalty for the subsoil use, the adjustment coefficients (from 0.01 to 0.97) apply depending on the type of raw material and the conditions of its extraction.
Compared to the rates at the end of 2022, the rates of production royalty for the extraction of oil, condensate and natural gas did not change in 2023. In October 2024, the VRU adopted the law that, inter alia, provided for the abolition of the reduced production royalty rate when the actual sale price of natural gas for the reporting period is USD 150 or less per 1000 cubic meters. The law entered into force on 01.12.2024
The rates of the production royalty for the subsoil use or the production royalty under PSA were determined in the PSA, but they could not be lower than those established by Section IX of the Tax Code at the time of the PSA conclusion. In 2023, special production royalty rates continued to apply: under the PSA for oil and condensate, the production royalty for the subsoil use was calculated at a rate of 2% of the value of the mining enterprise's commodities, and for natural gas, the production royalty for the subsoil use was calculated at a rate of 1.25% of the value of the mining enterprise's commodities.
For legal entities that meet the specified criteria for state ownership, a special rate is provided for taxation of additional volumes of hydrocarbon raw materials extracted as a result of the implementation of existing or new investment projects that provide for an increase in hydrocarbon raw materials extraction in the amount of 2% of the cost of additional extraction of the relevant hydrocarbon raw material for:
-
►
subsoil areas with deteriorated mining and geological conditions (which are difficult to extract) or depleted during development in previous periods;
-
►
individual operating wells after major repairs;
-
►
wells restored from the liquidated ones, new wells or groups of wells located in such subsoil areas.
The procedure for selecting and approving new investment projects that provide for the increase in hydrocarbon raw materials extraction, the procedure for determining additional volumes of hydrocarbon raw materials, as well as the procedure for monitoring the implementation of such investment projects (programs) are determined by the CMU upon submission by the Ministry of Economy.
The list of subsoil fields and/or subsoil areas where the new investment projects are implemented is determined by the Ministry of Energy.
Royalty rates for subsoil use in hydrocarbon production in 2022
| Object of taxation | Rate |
|---|---|
| Oil | |
| from deposits at a depth of up to 5000 m | 31 % |
| from deposits at a depth of more than 5000 m | 16 % |
| extracted under PSA | 2% |
| Condensate | |
| from deposits at a depth of up to 5000 m | 31 % |
| from deposits at a depth of more than 5000 m | 16 % |
| extracted under PSA | 2% |
| Natural gas (of any origin) | |
| from deposits at a depth of up to 5000 m | 29 % |
| Starting from March 2022: from deposits at a depth of up to 5,000 m | 14,5 % - 65 % |
| Before March 2022: from deposits at a depth of more than 5,000 m, including natural gas sold for household consumers | 14 % |
| Starting from March 2022: from deposits at a depth of more than 5,000 m | 7 % - 31 % |
| from deposits in subsoil areas (fields) within the continental shelf and/or exclusive (maritime) economic zone of Ukraine | 11 % |
| extracted under JVA | 70 % |
| extracted under PSA | 1,25 % |
| Before March 2022: natural gas extracted from new wells from deposits wholly or partially located at a depth of up to 5,000 m | 12 % |
| Starting from March 2022: natural gas extracted from new wells from deposits wholly or partially located at a depth of up to 5,000 m | 6 % - 36 % |
| Before March 2022: natural gas extracted from new wells from deposits wholly or partially located at a depth of more than 5,000 m | 6 % |
| З березня 2022 року: природний газ, видобутий із нових свердловин з покладів, які повністю або частково залягають на глибині понад 5000 метрів | 3 % - 18 % |
When calculating the production royalty for subsoil use, adjustment coefficients (from 0.01 to 0.97) applied depending on the type of raw material and the conditions of its extraction.
Compared to the rates applicable in 2021, the rates of production royalty for the extraction of oil, condensate and natural gas increased in 2022.
The rates of the production royalty for subsoil use or the production royalty under PSA were determined in the PSA, but they could not be lower than those established by Section IX of the Tax Code at the time of the PSA conclusion. In 2022, special production royalty rates continued to apply: under the PSA for oil and condensate, the production royalty for subsoil use for the extraction of minerals was calculated at a rate of 2% of the value of the mining enterprise's commodity products, while for natural gas, the production royalty for subsoil use for the extraction of minerals was calculated at a rate of 1.25% of the value of the mining enterprise's commodity products.
Temporary specific features of payment of production royalty for the subsoil use for gas extraction
In 2023–2024, temporary specific features of production royalty payment for subsoil use related to natural gas extraction remained in effect for volumes of natural gas injected into storage facilities and not sold. In particular:
-
►
The production royalty for the subsoil use for natural gas extraction is temporarily not paid for the volumes of extracted natural gas which were pumped into gas storage facilities.
-
►
The amount of tax liabilities of production royalty for the subsoil use for natural gas extraction in each reporting period is calculated for the volumes of the extracted natural gas in the relevant tax (reporting) period but will be paid in the amount corresponding to the volumes of natural gas sold in such tax (reporting) period.
-
►
The amount of the production royalty due is calculated as the difference between the declared tax liabilities and the product of the volume of the pumped natural gas and the weighted average effective rate.
-
►
In the case of the sale of natural gas pumped into gas storage facilities, the amount of tax liabilities of production royalty is calculated according to the FIFO principle, based on the weighted average effective production royalty rate and the volume of gas written off from the balance sheet of gas stored in the gas storage facility.
-
►
Production royalty payers are required to keep separate records of the volumes of natural gas extracted and sold.
-
►
If the balance of unsold gas is available at the end of the month in which martial law is terminated, the amount of the tax liabilities will be paid in the period when the sale takes place, but no later than the end of the third month after the termination or cancellation of martial law in the territory of Ukraine.
The temporary provisions do not apply to the volumes of natural gas sold to Naftogaz of Ukraine NJSC to form a natural gas resource for the needs of household consumers and heat energy producers.
The special rules for paying production royalty will be in effect until the last day of the month in which martial law is lifted in the territory of Ukraine.
For the purposes of reducing the tax burden on natural gas production companies following the March 2022 changes to the production royalty calculation rules, a temporary special mechanism for the payment of production royalty for subsoil use in respect of volumes of natural gas injected into gas storage facilities and not sold was introduced in April 2022. In particular:
-
►
The production royalty for subsoil use for natural gas extraction was temporarily not paid in respect of volumes of natural gas extracted but not sold during the relevant reporting periods and injected into gas storage facilities.
-
►
The amount of tax liabilities for the production royalty for subsoil use for natural gas extraction in each reporting period was calculated based on the volume of natural gas extracted during the relevant tax (reporting) period, but was payable only in the amount corresponding to the volume of natural gas sold during such tax (reporting) period.
-
►
The amount of production royalty payable was calculated as the difference between the declared tax liabilities and the product of the volume of natural gas injected into storage facilities and the weighted average effective production royalty rate.
-
►
In the case of the sale of natural gas injected into storage facilities from April 2022 onwards, the amount of production royalty liabilities was calculated according to the FIFO principle, based on the weighted average effective production royalty rate and the volume of gas written off from the balance sheet of gas stored in the gas storage facility.
-
►
Production royalty payers were required to keep separate records of the volumes of natural gas extracted and sold.
-
►
If a balance of unsold gas remained at the end of the month in which martial law was terminated, the amount of tax liabilities would be paid in the period when the sale took place, but not later than the end of the third month following the termination or cancellation of martial law in the territory of Ukraine.
The temporary provisions did not apply to volumes of natural gas sold to Naftogaz of Ukraine NJSC to form a natural gas resource for household consumers and heat energy producers.
The special rules for the payment of production royalty will remain in effect until the last day of the month in which martial law is terminated in the territory of Ukraine.
In 2021, special production royalty rates were in effect: under the PSA for oil and condensate, the production royalty for subsoil use for the extraction of minerals was calculated at a rate of 2% of the value of the mining enterprise’s commodity products, and for natural gas, the production royalty for subsoil use for the extraction of minerals was calculated at a rate of 1.25% of the value of the mining enterprise’s commodity products.
The size of rent rates for the use of subsoil in the case of extraction of hydrocarbon raw materials in 2021
| Object of taxation | Rate |
|---|---|
| Oil | |
| from deposits at a depth of up to 5000 m | 31 % |
| from deposits at a depth of more than 5000 m | 16 % |
| Condensate | |
| from deposits at a depth of up to 5000 m | 31 % |
| from deposits at a depth of more than 5000 m | 16 % |
| Natural gas (of any origin) | |
| from deposits at a depth of up to 5000 m | 29 % |
| Starting from March 2022: from deposits at a depth of up to 5,000 mfrom deposits at a depth of more than 5,000 m, sold for the needs of household consumers | 14 % |
| from deposits in subsoil areas (fields) within the continental shelf and/or exclusive (maritime) economic zone of Ukraine | 11 % |
| from deposits at a depth of up to 5,000 m, sold for the needs of household consumers | 29 % |
| from deposits at a depth of more than 5,000 m, sold for the needs of household consumers | 14 % |
| extracted under JVA | 70 % |
| natural gas extracted from new wells from deposits wholly or partially located at a depth of up to 5,000 m (except for natural gas extracted under JVA) | 12 % |
| natural gas extracted from new wells from deposits wholly or partially located at a depth of more than 5,000 m (except for natural gas extracted under JVA) | 6 % |
Compared to the rates applicable in 2020, the rates of production royalty for the extraction of oil, condensate and natural gas did not change in 2021.
The size of rent rates for the use of subsoil in the case of extraction of hydrocarbon raw materials in 2020.
| Object of taxation | Rate |
|---|---|
| Oil | |
| extracted from deposits located at depths of under 5,000 m | 31 % |
| extracted from deposits located at depths of over 5,000 m | 16 % |
| Condensate | |
| extracted from deposits located at depths of under 5,000 m | 31 % |
| extracted from deposits located at depths of over 5,000 m | 16 % |
| Natural gas (of any origin) | |
| extracted from deposits located at depths of under 5,000 m | 29 % |
| extracted from deposits located at depths of over 5,000 m | 14 % |
| extracted from deposits in subsoil fields located within the continental shelf and/or the exclusive (maritime) economic zone of Ukraine | 11 % |
| extracted from deposits located at depths of under 5,000 meters, sold for households’ needs | 29 % |
| extracted from deposits located at depths of over 5,000 meters, sold for households’ needs | 14 % |
| produced under JVA | 70 % |
From January 1, 2018, a stimulating royalty rate was introduced for extracting natural gas, produced from new wells in the amount of 12% of the deposits that are fully or partially located at depths of under 5000 meters, and 6% of the deposits that are fully or partially located at a depth of over 5000 meters. In 2019, royalty rates for extracting oil were standardized
In 2018, 5% of the production royalty for extracting hydrocarbons were transferred to the general fund of the local budgets, which was distributed depending on the location (place of extraction) of the respective natural resources. The amount of 95% of this tax was transferred to the State budget, except for the payments made for the use of natural resources within the continental shelf or exclusive (marine) economic territory of Ukraine, which had to be remitted to the State budget in full

The basis of taxation for minerals, other than hydrocarbon raw materials and iron ores, is their value, which was calculated according to the greater of two values: according to the actual sale prices or according to the estimated value of the mineral.
Calculation of the actual selling price of a mineral
As a general rule, the amount of revenue generated from the sale of a particular mineral commodity during the reporting period was reduced by the exhaustive list of deductible expenses established by the Tax Code.
In the years 2020-2024, as in previous years, the expenses included:
- the costs of delivering products to the consumer and the costs of pre-sale preparation of goods.
- In the absence of sales of extracted minerals or if there is a need to subject such extracted minerals to technological operations that are not provided for by primary processing for the introduction of extracted minerals into civil circulation, the tax base for production royalty is determined based on the estimated value.
- a special rule is used for calculating the value of uranium and gold ores extracted from primary deposits.
The unit cost of a type of mineral extracted was calculated as the ratio of the amount of income from the sale of a type of mineral extracted (with deduction of costs) and the volume (quantity) of the corresponding type of mineral sold of minerals, which is determined according to the accounting data of stocks of finished products of such payer.
At the end of 2024, laws came into force that, inter alia, changed the mechanism for calculating the value of extracted minerals for the purposes of production royalty by establishing a minimum tax base for paying production royalty for:
-
►
granite: USD 6.5 per ton or more
-
►
sand: USD 5 per ton or more
-
►
kaolin: USD 300 per ton or more, and from 01.01.2025 – 120 USD per 1 ton if extracted from mineral raw materials recognized as suitable for primary processing (enrichment), USD 40 per 1 ton if extracted from mineral raw materials recognized as unsuitable for primary processing (enrichment).
Production royalty rates for subsoil use in case of extraction of types of minerals, other than hydrocarbons and iron ore, 2022 - 2024
| Object of taxation | Rate |
|---|---|
| Ore (metal-bearing (metallic), including ores) minerals: | |
| ferrous (other than iron one), colour and alloying metals | 6.25 % |
| uraniferous, and other than uriniferous ores of ferrous, colour and alloying metals | 5 % |
| Energy minerals | |
| coking coal | 1.5 % |
| energy coal | 0.75 % |
| anthracite | 1 % |
| brown | 1 % |
| Non-energy, non-ore (non-metal-containing (non-metal)) minerals, including quartz sand, groundwaters, fire clay, high-melting clay, limestone, granite, gneiss, therapeutic muds and others, except for amber) | 5 % |
The size of rent rates for the use of subsoil in the case of extraction of other types of minerals, except for hydrocarbons, in 2021.
| Object of taxation | Rate |
|---|---|
| Ore (metal-bearing (metallic), including ores) minerals: | |
| ferrous (other than iron one), colour and alloying metals | 6,25 % |
| uraniferous, and other than uriniferous ores of ferrous, colour and alloying metals | 5 % |
| Iron ores | 11-12 % |
| Energy minerals | |
| coking coal | 1,5 % |
| energy coal | 0,75 % |
| anthracite | 1 % |
| brown | 1 % |
| Non-energy, non-ore (non-metal-containing (non-metal)) minerals, including quartz sand, groundwaters, fire clay, high-melting clay, limestone, granite, gneiss, therapeutic muds and others, except for amber) | 5 % |
The size of rent payment rates for the use of subsoil in the case of extraction of other types of minerals, except for hydrocarbons and iron ore, in 2020
| Object of taxation | Rate |
|---|---|
| Ore (metal-bearing (metallic), including ores) minerals: | |
| ferrous (other than iron one), colour and alloying metals (before 23.05.2020 | 5 % |
| ferrous (other than iron one), colour and alloying metals (from 23.05.2020) | 6,25 % |
| uraniferous, and other than uraniferous ores of ferrous, colour and alloying metals | 5 % |
| iron ore (before 23.05.2020) | 8 % |
| iron ore (from 23.05.2020) | 11-12 % |
| Energy minerals | |
| coking coal | 1,5 % |
| energy coal | 0,75 % |
| anthracite | 1 % |
| brown | 1 % |
| Non-energy, non-ore (non-metal-containing (non-metal)) minerals, including quartz sand, groundwaters, fire clay, high-melting clay, limestone, granite, gneiss, therapeutic muds and others, except for amber) | 5 % |
From 23.05.2020, the rate of production royalty for the extraction of ferrous metals (except iron ores), non-ferrous and alloy metals was increased and constituted 6.5%, for the extraction of iron ore — 12%, if the average value of iron ore for the tax (reporting) period is USD 70 or more according to IODEX 58% FE CFR China, officially determined by the world news agency Platts, or 11%, if such average cost was less than USD 70, the rates and conditions for the application of certain adjusting coefficients to production royalty rates also were changed.

During 2023–2024, the rules governing the production royalty for subsoil use related to iron ore extraction remained unchanged.
Since the beginning of 2022, the rules governing the production royalty for subsoil use in relation to iron ore extraction have been amended as follows:
-
►
The tax base is calculated using only the actual selling price, rather than a comparison of the two values. The actual selling price is determined according to the general rules provided for the minerals other than hydrocarbons.
-
►
The production royalty rate for the extraction of iron ore were differenced depending on the average actual selling price determined as the average cost of iron ore according to the Platts IODEX 62% FE CFR China.
Production royalty rates for iron ore mining 2022 - 2024
| Object of taxation | Rate |
|---|---|
| Iron ore, if the average cost of iron ore according to the IODEX 62% FE CFR China index, officially determined by the global information agency Platts, for the tax (reporting) period is: | |
| 100 USD or less | 3.5 % |
| More than 100 USD but does not exceed 200 USD inclusively | 5 % |
| More than 200 USD | 10 % |
Production royalty for subsoil use for the extraction of minerals other than hydrocarbons
Production royalty for the extraction of minerals (other than hydrocarbons) of national importance was distributed between the general funds of the budgets as follows:
-
►
70% was transferred to the general fund of the State Budget of Ukraine.
-
►
25% — to the general fund of the regional budgets/ Kyiv city budget.
-
►
5% — to the general fund of the local government budgets.
Production royalty for the extraction of minerals of local importance was paid to the budget of the local government at the location (place of extraction) of the relevant natural resources in full.
Payment reconciliation
According to the results of the reconciliation of payments for 2024, the amount of state revenues from the production royalty from the extractive companies, according to state authorities, amounted to UAH 50,130,995.74 thousand, and according to the data of the extractive companies it was UAH 50,130,980.90 thousand. The amount of discrepancies between the data of taxpayers and the data of state authorities, according to the results of the initial request, amounted to UAH 2,331,760.61 thousand, and after reconciliation and clarifications, the amount of discrepancies is UAH 14.84 thousand.
According to the results of the reconciliation of payments for 2023, the payments in favour of the state from the production royalty from the extractive companies, according to the state authorities, amounted to UAH 57,990,377.32 thousand, and UAH 57,990,188.66 thousand according to the data of the extractive companies. The discrepancy between the data of the taxpayers and the data of state authorities, according to the results of the initial request, amounted to UAH 6,818,281.82 thousand, and after the reconciliation and clarifications, the discrepancy is UAH 188.66 thousand.
According to the results of the reconciliation of payments for 2022, the amount of state revenues from the production royalty from the extractive companies, according to state authorities, amounted to UAH 81,988,108.94 thousand, and according to the data of the extractive companies it was UAH 81,986,286.60 thousand. The amount of discrepancies between the data of taxpayers and the data of state authorities, according to the results of the initial request, amounted to UAH 3,266.44 thousand, and after reconciliation and clarifications, the amount of discrepancies is UAH 1,822.33 thousand.
Considering the provisions of the Terms of Reference, neither the reconciliation of data on payments in favour of the state nor the analysis of discrepancies was performed for the EITI Report 2021. Instead, payment data were disclosed unilaterally, without reconciliation.
According to the results of the reconciliation of payments for 2020, the amount of state revenues from the production royalty from the extractive companies, according to state authorities, amounted to UAH 48,506,126.71 thousand, and according to the data of the extractive companies it was UAH 48,510,026.58 thousand. The amount of discrepancies between the data of taxpayers and the data of state authorities, according to the results of the initial request, amounted to UAH (215,358.74) thousand, and after reconciliation and clarifications, the amount of discrepancies is UAH (3 899,87) thousand.
According to the results of the reconciliation of payments for 2019, the amount of state revenues from the production royalty from the extractive companies, according to state authorities, amounted to UAH 42,547,316.09 thousand, and according to the data of the extractive companies it was UAH 42,547,471.66 thousand. The amount of discrepancies between the data of taxpayers and the data of state authorities, according to the results of the initial request, amounted to UAH 95,785.95 thousand, and after reconciliation and clarifications, the amount of discrepancies is UAH (155,57) thousand.
According to the results of the reconciliation of payments for 2018, the amount of state revenues from the production royalty from the extractive companies, according to state authorities, amounted to UAH 40,672,021.77 thousand, and according to the data of the extractive companies it was UAH 40,661,323.35 thousand. The amount of discrepancies between the data of taxpayers and the data of state authorities, according to the results of the initial request, amounted to UAH 1,510,741.81 thousand, and after reconciliation and clarifications, the amount of discrepancies is UAH 10 698,41 thousand.
DATA OF REPORTS OF BUSINESS ENTITIES
| Year | Company name | USREOU Code | Code according to the Codifier of administrative-territorial units and territories of territorial communities | Name of the budget program | Special permit for subsoil use | Agreement on the use of subsoil | A mineral that is mined | Budget revenue classification code | Type of payment | Payment currency | Due, thousand | Paid, thousand | Note | |||
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Registration number | Issue date | Counterparty according to the agreement | Registration number | Date of conclusion | ||||||||||||
Land fee
Land fee (a component of property tax, which is a local tax) is levied in the form of land tax and rent payment for land plots of state and municipal property. The companies engaged in the extraction of natural resources and their transportation by pipelines pay land fee on a general basis.
The tax base is the normative monetary assessment of land plots taking into account the indexation coefficient or the area of land plots (if the assessment has not been carried out). The amount of land fee depended on a number of factors, including the location, functional intended use and the availability of a normative monetary assessment of the land plot.
In 2024, a wide list of land tax threshold rates and rent thresholds, determined depending on the above characteristics, remained unchanged compared to 2023.
In 2023, the broad list of land tax and rent payment cap rates, determined based on the above characteristics, remained unchanged compared to 2022.
In 2023-2024, the land fee for land plots provided to mining enterprises for the extraction of minerals and the development of mineral deposits was charged at the rate of 25% of the tax calculated according to the rules of the Tax Code.
In 2023-2024, the land fee was transferred to the general fund of local government budgets at the location of the land plot in full.
Temporarily, from March 2022 until the end of the year following the year in which martial law is terminated, no land fee is charged or paid for land plots located in territories where hostilities are ongoing or have been conducted, or in territories temporarily occupied by russian armed forces, as well as for land plots identified by regional military administrations as contaminated with explosive objects and/or containing fortification structures. The list of territories where hostilities are ongoing or have been conducted, or which are temporarily occupied by russian armed forces, is determined by the CMU.
In 2018 - 2022, the land fee was transferred to the general fund of local government budgets at the location of the land plot in full.
In 2018 - 2022, the land fee for land plots provided to mining enterprises for the extraction of minerals and the development of mineral deposits was charged at the rate of 25% of the tax calculated according to the rules of the Tax Code.
According to the results of the reconciliation of payments for 2024, the amount of state revenues from land fees from extractive companies, according to state authorities, amounted to UAH 3,695,216.41 thousand, and according to extractive companies, it was UAH 3,670,312.09 thousand. The amount of discrepancies between the data of taxpayers and the data of the state authorities, according to the results of the initial request, amounted to UAH 28,090.58 thousand, and after reconciliation and clarifications, the amount of discrepancies amounted to UAH 24,904.32 thousand.
According to the results of the reconciliation of payments for 2023, the revenues in favour of the state in the form of land fee from legal entities from extractive companies, according to state authorities, amounted to UAH 2,932,549.16 thousand, and UAH 2,909,028.04 thousand according to extractive companies. The discrepancies between the taxpayers’ data and the state bodies' data, according to the results of the initial request, amounted to UAH 29,485.94 thousand, and after reconciliation and clarifications, the discrepancies amounted to UAH 23,521.12 thousand
According to the results of the reconciliation of payments for 2022, the revenues in favour of the state in the form of land fee from legal entities from extractive companies, according to state authorities, amounted to UAH 2,519,988.49 thousand, and UAH 2,499,114.69 thousand according to extractive companies. The discrepancies between the taxpayers’ data and the state bodies' data, according to the results of the initial request, amounted to UAH 20,851.39 thousand, and after reconciliation and clarifications, the discrepancies amounted to UAH 20,873.79 thousand
Considering the provisions of the Terms of Reference, neither the reconciliation of data on payments in favour of the state nor the analysis of discrepancies was performed for the EITI Report 2021. Instead, payment data were disclosed unilaterally, without reconciliation.
According to the results of the reconciliation of payments for 2020, the revenues in favour of the state in the form of land fee from legal entities from extractive companies, according to state authorities, amounted to UAH 1,515,479.13 thousand, and UAH 1,500,918.98 thousand according to extractive companies. The discrepancies between the taxpayers’ data and the state bodies' data, according to the results of the initial request, amounted to UAH 12,395.15 thousand, and after reconciliation and clarifications, the discrepancies amounted to UAH 14,560.15 thousand
According to the results of the reconciliation of payments for 2019, the revenues in favour of the state in the form of land fee from legal entities from extractive companies, according to state authorities, amounted to UAH 1,984,259.25 thousand, and UAH 1,967,062.98 thousand according to extractive companies. The discrepancies between the taxpayers’ data and the state bodies' data, according to the results of the initial request, amounted to UAH 38,478.45 thousand, and after reconciliation and clarifications, the discrepancies amounted to UAH 17,196.27 thousand
According to the results of the reconciliation of payments for 2018, the revenues in favour of the state in the form of land fee from legal entities from extractive companies, according to state authorities, amounted to UAH 1,361,486.64 thousand, and UAH 1,342,655.45 thousand according to extractive companies. The discrepancies between the taxpayers’ data and the state bodies' data, according to the results of the initial request, amounted to UAH 62,138.79 thousand, and after reconciliation and clarifications, the discrepancies amounted to UAH 18,831.19 thousand
Data from reports of business entities
| Year | Company name | USREOU Code | Code according to the Codifier of administrative-territorial units and territories of territorial communities | Name of the budget program | Special permit for subsoil use | Agreement on the use of subsoil | A mineral that is mined | Budget revenue classification code | Type of payment | Payment currency | Due, thousand | Paid, thousand | Note | |||
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Registration number | Issue date | Counterparty according to the agreement | Registration number | Date of conclusion | ||||||||||||
Reimbursement of Pension Fund expenses for payment and delivery of preferential pensions
According to the results of the reconciliation of payments for 2024, the amount of the state revenues from the reimbursement of Pension Fund expenses for payment and delivery of preferential pensions from extractive companies, according to the state authorities, amounted to UAH 1,752,884.18 thousand, and according to the data of the extractive companies, it was UAH 1,753,316.82 thousand. The amount of discrepancies between the data of the taxpayers and the data of the state authorities, according to the results of the initial request, amounted to UAH 460,424.17 thousand, and after reconciliation and clarifications, the amount of discrepancies amounted to UAH (432.64) thousand.
Royalty for transportation
For royalty for the transportation of oil and petroleum products, the object of taxation was the actual volume transported through the territory of Ukraine in the tax period, for ammonia – the sum of the products of the distances of the relevant routes of its transportation (transmission), agreed on between the royalty payer and the customer for the relevant tax (reporting) period, and the volumes of ammonia transported (transmitted) by each transportation route.
The companies operating the trunk pipeline facilities and provide (organize) services for the transportation (transmission) of products through such pipelines pay production royalty at the following rates:
| Object of taxation | Rate in 2020-2024 |
|---|---|
| Transportation of 1 ton of oil or petroleum products | USD 0.56 |
| Transit transportation of 1 ton of ammonia per 100 km distance of the relevant routes of its transportation | USD 2.4 |
If there is a change in transportation tariffs, a respective adjustment coefficient applies to the royalty rates, except for the royalty rate for transit transportation of ammonia and for transportation of oil through the trunk oil pipelines for consumers in Ukraine.
In 2020-2024, payments under this type of rent were fully credited to the general fund of the State Budget.
Reconciliation of royalty for transportation
According to the results of the reconciliation of payments for 2024, the amount of state revenues from royalty for transportation from the extractive companies, according to the state authorities, amounted to UAH 674,112.39 thousand, and according to the extractive companies, it was UAH 674,112.39 thousand. There are no discrepancies.